 Time for a wee break. In the last week, I've been researching Zara and H&M a little, to better understand the retail-sector and the fashion-segment. I'll probably have to do a follow-up to this post, as there is lots to say about both businesses, but here's some initial impressions, nevertheless.
First off, H&M appears a lot more clean in its approach. Judging by the annual reports alone, H&M not only has a 2007-edition (Zara is only up to 2006), but it is also only 85 pages long (presented in an eco-friendly 2-pages-per-side way), while for Zara, or actually Inditex, it's mother-company, the annual report is a stunning 450 page long!
Now, that's really not all that surprising, as Inditex is composed of a number of companies, and it is extremely vertically integrated, while H&M employs the Nike or Apple model—it designs and it retails, but it doesn't produce.
Why this is so, I can only guess, is due to their origins. Inditex comes from Spain, traditionally a low-waged country, while H&M is Swedish, not a low-waged country. Similar to IKEA, I imagine it was an economical decision to outsource most of its supplies.
It's very hard to separate Inditex from Zara, as both are founded and owned by the same person, Amancio Ortega Gaona, Spain's richest man. Zara has been in existence since 1975. H&M was founded by a Swede, Erling Person, in 1947, who ran the company to ca. the mid-90s, but which has continued to be a family firm.
Their business-philosophies are fairly similar, a low-cost, high-quality approach to fashion, as opposed to traditional brands, where quality most often equals price.
Zara made lots of headlines with its extremely high turnover of products—it produces around 11,000 items annually (as oppsed to 2,000-4,000 for other retailers); 15-20% produced before, 50-60% at the start of the season, and the rest during. If a product fails to do well, it is usually removed after a week in stores.
H&M made headlines with its celebrity-marketing, which is noteworthy, as Zara has virtually no marketing. Instead, because it has such a high turn-over of goods, customers tend to visit it more often, expecting new things—an average of 17 times per year vs. 3 times for other stores!
Both employ mostly a wholly-owned retail-strategy, except in countries where this is not possible. And both are very advanced in their use of IT to manage logistics and production, which is definitely seems to be a key-characteristic of delivering fashion quickly and find ways to decrease costs.
H&M's largest markets are Germany, Sweden, the USA, Spain, and the Netherlands (in terms of sales). For Zara it is Spain, France, Germany, and Mexico (in number of stores).
That's all I can think of in 30 mins or less…
 Take a look at this quote, which I posted a few days ago:
"There should be a rule: before helping the environment in one market, we should be required to think through the impacts on other markets." (source: Freakonomics blog).Or, to put it differently, every action has a (sometimes equal) reaction (I think the traditional phrasing ignores the human element). The idea that everything is interconnected is both fun to right-brained generalists like me (not a compliment), and scary at the same time. The global economy is very complex and, I would say, impossible to regulate.
There's a couple of things going on the world, which I'm sure everyone is aware of. There's a number of wars, there's the weakened dollar, there's some kind of housing-related recession going on, there's a shortage of oil, our planet is perceived as suffering and currently being saved (I hope), there's India and China, the rise of the Anglo-Saxon system, etc. etc.
And some of the biggest problems facing the food-industry (depending where you are in the chain), are rising food-prices, which relates to that oil-shortage (both in terms of pricing, but also because of alternative fuels using farm-products), the rise of India and China, and some other factors; and the costs of keeping green, which has largely been inspired by companies like Wal-Mart, but also by the (exaggerated) need for global diversity by customers (which the food-industry is also partially to blame for).
The solutions vary, and are, so far, very defensive in their nature. For the cost of going green, most pollution comes from transport and the solution is to either use the most eco-friendly way to go: on land, by train, across water, by ship; or to go local—which companies like Marqt seem to focus on, but which also comes with the pitfall of seasonal shortage.
For rising food-prices, again one solution is to go local, to save on transport and have some control over how farmers work, and be able to charge higher prices to the rising local-conscious consumer. But a bigger solution is for more food-production to happen (much of it currently goes to India & China, or to biofuels), and possibly from smaller farmers. The problem here is that it will take time (some estimate decades) for smaller farmers to get ready.
Both are definitely big picture-problems, and will take time to solve. One thing, I'm personally looking at, are micro-lending sites like Kiva.org, which put you into contact with local farmers, allowing you to help them out in your own way. From a Venture Voice interview with one of the founders, I understand that some of these investments happen within the context of a community, where each member keeps watch over the other's use and repayment of the funds, in order to ensure a good outcome, and so loans will continue to come in. But, while I think it's well worth the effort, this is still a small-picture solution to a much larger problem.
The way it looks right now, the solutions have to be planned in the long-term and on a large scale. There is definitely space in the farming-segment for more production to happen. In the mean time, food-prices will continue rise, as will the price of educating consumers to make more responsible choices. I like Tesco's approach in labelling the origins of their food and allowing people to make more carbon-friendly (locally focussed) decisions. But that doesn't solve the problem for farmers in remote areas of course.
Sigh, if you just got a headache, I sympathise, as I just got one too.
Further reading:
- NYTimes: Environmental Cost of Shipping Groceries Around the World
- Economist: The new face of hunger
- Buzzfeed: Food Hoarding
A VC: From Messes To Successes:
"The prescription for turning these messes into successes is really pretty straightforward. You need to build the team and bring in people who excel at the blocking and tackling and the PLANNING that most startups don't have the time or inclination to do. And you need to gradually change the culture of the business from one that is all about the product to one that is about the entire company. Sometimes, often times, that means changing the people around. And that's never easy. And it's even harder to change the people around when it was the initial team that made the product so popular in the first place. So you have to somehow find a way to add the 'operational' people without drowning out the 'product' people."
Eggbeater: Chef Owners Who Work The Line
I'm starting to think people should take a test before they open a restaurant. It will be like a triathlon: you must work the line, well, if not stellar. You must understand and be able to explain one P&L statement. You must understand why raw fish and cooked meat cannot share the same bin in the walk-in. You must understand how to make cookies, one dessert with chocolate that's not a molten chocolate cake and it would be great if you knew the difference between panna cotta and creme brulee. The test would list a series of questions and you would be graded on how much responsibility you took for your own actions or the actions of those you hired. For bonus points you might have to research why all the restaurants in your location before yours failed, or cooking in and creating a menu for a kitchen with no Latinos (or your State/ Country picks for easy-to-exploit-able peoples.)
Freakonomics: The Consequences of Being Green
There should be a rule: before helping the environment in one market, we should be required to think through the impacts on other markets.
I just discovered a new podcast called "Big Ideas" (iTunes-link), a series of lectures on anything from the impact of urbanisation on musical tastes, to designing menus for restaurants. Oh, and it's Canadian. Not that that's bad, but some parts of the lecture covered local conditions.
John Schneeberger starts his lecture (dated March 1, 2008) off with the basics of menu-design, namely that they should reflect three things:
- What you stand for? Aka. what kind of food do you like to work with?
- What demographics are you targeting? Income, religious issues, etc.
- What are the current trends? And are they for real or just a fad?
- Customer-decisions are always a trade-off between price and quality
- Traditionally, dishes consist of three components: protein, starch, and vegetables.
- What we understand as taste, actually comes from three sources: fat, salt, and sugar.
Schneeberger discussed three booming trends, vegetarianism, organic food, and local produce, and mentioned a number of challenges related to these.
 Vegetarian cooking
The thing to understand about this, is that it's generally cheaper. Schneeberger mentioned a 1:10 ratio when you compare the cost of producing vegetables to the cost of growing a cow. And while it's a booming trend, the industry, somewhat mis-guidedly, still often focusses on trying to replicate the taste of meat, which is impossible (think veggie-burgers, etc.).
Instead, they should be thinking about nutritional value— vegetarian food has been correlated with lower health-problems and is for that reason often recommended by doctors. The problem with these types of diets is of course that they are low in those qualities we would traditionally associate with taste: fat, salt, and sugar.
To create dishes that people actually enjoy, restaurants have to look globally, e.g. Asia, where more exotic vegetable components can bring some needed flavour to these dishes. I think he mentioned seaweed, but also stinky tofu (see pic), which is a type of fermented tofu and one of the few ways to naturally bring flavour to that type of protein.
The implication is that vegetarian food requires a significant amount of specialisation and is often hard to combine with meat-cooking.
Another complication arises from vegan (no dairy, honey, animal-derived products) versus lacto-ovo (incl. dairy, honey, animal-derived) cooking. The first makes it very hard to create a (traditionally) tasty dish. The second, lacto-ovo, allows for more flexibility, through the use of ingredients like eggs, which not only provide extra protein, but also bring a lot of flexibility to the kitchen. You can, for instance, make foam out if it, which would enable the creation of deserts & soups, etc.
Organic cooking
First of all (and I'm not sure if this is just restricted to Canada), an organic food label refers to the production method, not necessarily the quality and taste. Since organic food is more expensive, and taste is not guaranteed, you have to wonder if your clientele is willing to pay extra for that service (remember the trade-off between price & quality!).
The big selling-point here is the information about the product. People like to know how their food was produced; it has a certain value to know that there are no chemicals or genetically modified components in what you are eating. But again, that must be a value that is clearly advertised and which may not be important to every type of demographic.
Local produce
The advantage for the restaurant is that they can form better relationships with their suppliers, it's also cleaner in terms of carbon footprint (less transport), and it also has some marketing value to a certain demographic.
The disadvantage is that supply cannot be guaranteed during all seasons. Schneeberger mentioned something called a "100 mile diet" for instance, but restaurants catering to that need will probably have problems in the winter.
Thoughts
Overall, a pretty insightful lecture of the more exotic (and trendy) type of cooking and its trade-offs.
These types of specialisation are still pretty niche, require significant resources in terms of tools, know-how, and supplier-relations. But, if executed well, a niche can be extremely profitable.
I thought that it was interesting that all the traditional means of cooking, the ingredients and the taste-makers, were pretty incompatible with these newer trends. As such, you are essentially climbing up a hill, trying to educate the mass-market. At the same time, good execution, together with differentiation from the norm, seems like a formula for success.
 Just a short tweet.
I'm currently reading a Dutch book on the 2003 crisis at Ahold, but which is actually a historical account of how the corporation came to be. A couple of things I found interesting:
- Ahold actually stands for AH (Albert Heijn) Holdings
- We all know that things are cyclical, but it was interesting to read how a recession and high oil prices were a challenge that Ahold had to face in the 60s-70s, and how they managed to survive.
- In order to inspire Dutch people to shop more, they introduced a financing scheme for fridges, which people couldn't afford at that time. General Motors did a similar thing to help people afford their cars; seems like an interesting way to "upgrade" an economy.
- The fear of a socialist government drove Albert Heijn to look outwards and form Ahold (similar to why IKEA decided to globalise also).
- One of the consequences of politics at that time was the board of directors, meant to provide impartial guidance and represent the workers.
- They made extensive use of consultancies (often McKinsey) whenever they decided on a strategic trajectory.
- One of the directors was a big fan of Harvard Business Review :)
- They use the US as a source of knowledge on how to design their supermarkets. Later on, moving to the US was also seen as a way to increase that learning, as well as a new revenue-source.
- When AH moved to the US, they also brought their own ideas, like, eh, advertising (a terrible, terrible idea).
I took this title from a report on the future of Dutch supermarkets (English pdf). It identifies a number challenges to come, one of which is "stomach share," which is apparently a big deal because of the following three factors:
- Population decline: which translates into less consumers buying food
- Increased longevity: and older people have a lower caloric intake
- Increased awareness of health-issues: which also translates to a lower caloric intake.
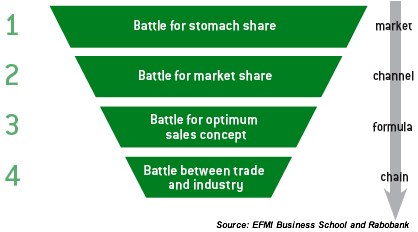
What the authors are seeing is that players from the bottom of the market (the discounters) are moving upwards, by broadening their assortment of goods, and players from the top of the market (luxury-stores) are moving downwards, by improving their prices. A number of underlying things are going on here: luxury-stores can become cheaper by improving the efficiency of their stores and sourcing cheaper brands. And discounters can increase their offering through their relationship with suppliers.
Following HBS-quote, from an article entitled "Finding success in the middle of the market", sheds some light how Tesco does it:
A company controls midfield by fielding a complete product line that includes backs and forwards. In its supermarkets, Tesco, the successful UK retailer, offers consumers three options—good, better and best—in most high turnover product categories. In addition, Tesco doesn't just sell groceries through one-size-fits-all supermarkets. Recognizing the need to shape as well as respond to an increasingly segmented market, Tesco reaches its consumers through at least seven different store formats, from convenient Tesco Express outlets at one end of the spectrum to full assortment hypermarkets at the other. But, within all its stores, Tesco implements the same merchandising principles: Better, Simpler, Cheaper.Can you guess who the loser is yet? Well, according to both the report and much data on the net, the losers are the new, innovative concepts, that may offer certain values to consumers on an ethical or health level, but are not able to reap the same advantages as more established players are.
That is also the answer why so many organic companies are being bought up by fmcg-companies. There's an interesting overview here; but if you want to follow one in real-time, check out this Inc. magazine blog run by Honest Tea, which has recently given away 40% of their company to Coca-Cola.
Of course that is only part of the answer. Consumers are not just focussed on price. And, while consumer-awareness of the global situation and their own health is clearly growing, that's not the whole answer either. People's lives are becoming ever more complex and convenience is a big selling point these days.
It's those companies that can combine a high level of consumer-responsiveness, together with assortment and price, that will capture the hearts of consumers. But I guess what is out, is the solo single-product-serving player in the market, purely focussed on softer advantages like "ethics," and forgetting that consumers still(!) have limited disposable income for their food-expenses, as well a limited time to engage in these activities.
 The argument for mass-production is that it enables innovations to become cheaper and hence raises the general quality of life of consumers. The argument against mass-production is a more controversial one: that it destroys the unique quality of, let's call it, art.
Starbucks is a very good example of those principles. It brought a higher standard of coffee to the American masses, who, according to Howard Schultz's Starbucks biography, had long been oppressed by low-quality coffee from retailers and coffeeshops alike. At the same time, as the recent crisis at Starbucks illustrates, it has reached a saturation-point: it has brought Starbucks-outlets to every corner in the US, as well as spawned a whole army of competitors, and its brand has become diluted. It has become a commodity.
Back to their roots?
The re-enstatement of Howard Schultz as CEO is a signal, that the business has lost some of its original spirit and is in need of a guiding light. A letter that is rumoured (!) to be written by Schultz confirms that Starbucks will be focussing on re-introducing that original spirit, as hard as that will prove to be. There's only so much that you can change, after your company has reached a certain size. It would, at this point, be like saying that McDonalds is planning to become your corner-restaurant where everybody knows your name and favourite food.
The innovative angle
A friend of mine made me aware of a new coffee-brewing machine on the market, called Clover, which promises to deliver a higher quality coffee to consumers, though also at a higher price. According to Bruce Milletto, a retail consultant to the coffee industry, "a typical American café spends around $50,000 on equipment, about one-quarter of which goes on an espresso machine. At $11,000, a Clover costs the same again." Thus the investment-proposition is not an attractive one to the average cash-strapped café, who would have to spend that kind of money and charge an expected $6 per cup to recuperate that cost.
Following the rules of mass-production, Starbucks + Clover makes for a match made in heaven, and so it is: Starbucks has in fact acquired Coffee Equipment Company, the four-year-old Seattle-based maker of the Clover coffee brewing machine, for an undisclosed sum.
Considering that Starbucks has long been threatened by the commoditisation of coffee in the US, through the birth of literarily 1000s of new franchisers who, on the surface, provide the same value-proposal, though perhaps at a lower quality and price, it makes sense to acquire one piece of machinery that makes a bit of difference in the eyes of certain consumers. Considering the recent partnership with Apple, I believe that these consumers share a similar taste and price-insensitivity, and since that segment appears to be growing, I believe that Starbucks made the right call. They appeal to the type of customer that will pay $6 for a cup, and with their economies of scale, that price is sure to drop to a slightly more acceptable level of (I guess) ca. $5.
The cultural angle
There is another side to this. The USA is not the world, and while Starbucks has been thriving over there, the Europeans (I can't speak for other continents) have enjoyed a coffee-culture for quite some time. For people like my parents, who are respectively citizens from Southern- and Western-Europe, and avid café-visitors, they would not even consider going to the Starbucks in the centre of their German hometown, because there are plenty of alternatives with more atmosphere, more identity. To them, Starbucks is like a McDonalds, a franchise that in fact shares many cultural values—bringing a good to the masses—and does so by building ecosystems of services—from music-retail to the happy-meal—to deepen the (commercial) relationships with its customers.
Consciously and subconsciously, I'm a sympathiser of "unique" café-outlets. I like spending time in them, sometimes hours at a time, read my newspaper in peace, and enjoy a reasonably good coffee at slightly less than $2 a cup. I don't actually care about spending twice that for a coffee, but all the Starbucks's I've been too (exclusively in Germany and the UK, I must admit), have been so devoid of atmosphere that I don't really spend more than a few minutes there, 30 max. The only thing that does attract me about them and similar stores, is that I can grab a cup-to-go, mostly in the summer, and enjoy it out in the sun.
As a citizen of Europe, I think I am a fan of the heritage of the traditional café and don't really want it to go. If that makes me "backwards" or conservative, I am sorry. I want the chance to enjoy a Turkish coffee in Brussels, an Italian coffee in Cologne, or simply a Dutch one here in Rotterdam. I enjoy knowing the history of a pub that has existed for over a 100 years in Antwerp, and the same in Maastricht, or Amsterdam. I want there to be a diversity, and most important, I want that choice to be mine. I don't want there to be a cloned coffeeshop on every corner.
One of the saddest things I heard, while I was in Belgrade last year, was the exactly such a historical café was replaced by a chain (and the coffee stunk too); and I was equally sad to see that nearly all of the traditional retailers I remember from before the war had been replaced by a cloned shopping-centre that would've made any Western city proud: from H&M to Footlocker.
Opponent: Starbucks?
Globalisation is a situation we must all deal with. Its oldest proponents are the FMCG-companies, who are focussed on producing the same good for millions of people. The question is whether coffeeshops should embrace the FMCG-principles like McDonalds and Starbucks clearly have.
Starbucks is a formidable opponent: it is both a roaster, a retailer, and an FMCG-producer. It is strong in the US, and has a significant presence in the rest of the world. It will not go away, And not all believe that their presence is all that disruptive. I don't either, as long as Starbucks knows its limits. There are parts of the world that do not share the same qualities as US-towns. Some cities have long histories and places of heritage that should perhaps not be housing a McDonalds or Starbucks.
In a way cafés are stuck. They need the kind of innovation that Clover brings, but they are not in a position to buy their way in. If they did, they too would have to become mass-marketeers, in order to recuperate that cost. Instead they need to focus on what they do best, and coffee-machine makers to do the same and just license their technology. And whether the latter is able or willing to do that is the question.
I'm not sure how much Clover was acquired for, no one is. And I'm not sure how far Starbucks is willing to go to ensure their qualitative and quantitative dominance of the market. Will they grab every new piece of technology that promises to introduce a higher quality of coffee to consumers, keep it for themselves, and leave the traditional cafés to differentiate themselves simply by their "culture"? Sheer business-principles dictate that they will.
Howard Schultz made me believe, in his book, that it was Starbucks' mission to bring better coffee to the world. Let's hope that a richer coffee does not come at the price of a blander world.
This piece is in fact incomplete. Optimally I should write up a list of actions for coffeeshops to take. However, I am not yet that familiar with all the business-issues facing these organisations and all of my suggestions would be targeted at growing in size and battling on similar terms as a national or global player. And I'm pretty sure that many would not be willing to do that. So I think I'll wait until I have a more objective grasp—from all angles—on the situation, before giving practical advice. Feel free to provide me with that objectivity through your comments.
 Just read an interview with Ford's ex-CEO Jacques Nasser on the training programs that were prevalent at that time (2000). He justified their need, by outlining the history of the car-industry between 1905 and now.
- 1905-1920s - colonisation of car-companies: smaller replicas of car-factories in the US were being built abroad. Hardly any competition.
- 1920s-1950s - nationalism: lots of countries were building their own national vehicles. Competition mostly on a regional level.
- 1960s-1980s - regionalism: the rise of trading-blocks (NAFTA, EU, etc.) and as a response the functional/regional division of companies.
- 1980+ - globalisation: global competitors, more markets, more divergence of consumers, more need for people/ideas/growth.
The situation at Ford
The result of the last period is that there are more Ford-people around the globe to manage, that more markets need to be served with different needs, and that the company that can generate economies of scale & scope, while being most consumer-orientated wins.
Two strategic priorities are at play here: consumers only see a part of the car, which means that the hidden qualities can be mass-produced; and consumers value those qualities most matched with their environment—e.g. in Brazil, so I read, roads are abysmal (if any Brazilian reads this, correct me), and good suspension is highly valued. In China, luxury models are mostly driven by chauffeurs, while the consumer sits in the back, hence he/she values luxury in that part of the car.
In this scenario, two types of qualities are valued with people: to understand the corporate qualities of Ford and make decisions that favour its mass-market strategies; and those that understand the local environment and can design car-offerings tailored to local needs.
Social operating mechanisms at Ford
Ford, at the time of the interview, had about 12 programs aimed at promoting these skills. The ones mentioned, included: Capstone, which is aimed at (24) executives; Executive partnering, aimed at (12) promising managers; Business leadership initiative, aimed at the whole organisation; and a weekly email-newsletter, called "Let's chat about business," also aimed at the whole organisation.
Methods + Aims were:
- Team-building - to get people to work more closely together / develop a corporate culture
- Teaching - to get people to understand the priorities at a corporate level, rather then just at a divisional/functional level
- Projects - to get people to come up with problems plaguing their organisations at that time and develop creative solutions to them.
- Shadowing - to develop leaders
Thoughts
Several thoughts going through my head at the moment. I am both uncertain how relevant this is to the SME-environment, and at the same time I do a lot of "social engineering" and can certainly think of a few cases in my past where a certain structure would have benefited the small teams I worked in. I'll probably write a third post about the SME-perspective at some point in the future.
My favourite way to picture "social engineering" however, is through designing processes that bring elements of the organisation together with customers and "raw-inputs" (new technologies, future employees, and partners, etc.). Maybe, I'll write about that at some point too.
Of course, I always appreciate the reader's perspective on this. Social programs at an SME-level, good for team-building or bad because it distracts from survival-priorities?
The picture is courtesy of articlescaravan.com
 I'm still "on a break," but stumbled across this interesting titbit from a book on warehousing-practices. If you don't like reading lists, too bad because it's interesting, but I've also summarised the key-points in the end.
China
- Low labour and land-cost, but high equipment costs, translate into large (e.g. 250,000 square feet), low warehouses like in the US, but often lacking even a forklift.
- Certain goods like consumer electronics, are of such high value, have a short life-cycle, and thus a lower inventory-cost, that expenditure in state-of-the-art technology is justified.
- Certain cost-saving practices, like removing the pallets from shipments in order to ship more goods, cause some inefficiencies other countries, like, eh, re-adding pallets.
East Asia
- A traditional focus on personal relationships and less on computational models, means there's a lack of data and opportunities for improving performance are not well-developed.
- The most active economic areas are separated by lots of water, which means lots of product conveyed by air (for high-value or time-sensitive products) or ship (for bulky items or commodities). The high costs associated with this, are incentives to consolidate freight.
- Therefore, more strong regional hubs, like in Hong-Kong and Singapore, are expected to emerge.
Europe
- High labour-costs and an inflexibility of the work force have lead European warehouses to be more advanced in terms of automation.
- A growing common market will also lead to more economies of scale in the future, leading to larger, centralised warehouses.
India
- Characterised by cheap labour and land-cost, but relatively expensive capital costs (machinery and the like) and an underdeveloped infrastructure (both physical & administrative).
- The markets being supplied are generally local and not very wealthy, which leads to the SKUs not being high cost and there being little incentive to increase efficiency through capital expenditure (IT).
- Global demand means that larger distribution centres are being built around large ports like Mumbai (Bombay). The lack of land there is leading to high prices, comparable to Singapore/Hong-Kong.
North America
- Characterised by a culture of mass-consumption and a uniformity of the market and distribution infrastructure, which translates into large centralised warehouses and accelerating rates of product flow.
- Warehouses are often situated in the countryside surrounding metropolitan areas, which is cheaper, while being well-connected.
- A good telecommunications-infrastructure enables better supply-chain co-ordination; Warehouse management systems are generally advanced, and the rich data leads to better tracking and performance.
- High labour-cost are off-set by using cheaper migration-workers
Singapore, Hong Kong, Japan
- Due to a lack of land and high labour-cost, warehouses tend to be built high.
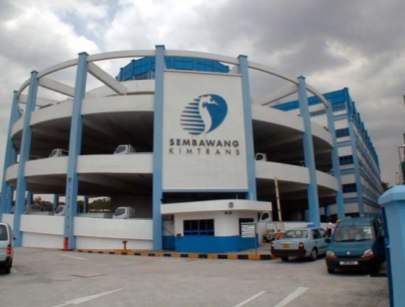
- Elevators are one bottleneck, caused by this style of building, however a Singapore warehouse has found a solution to this: A multi-floor facility with no automation or elevators, but, instead, a spiral truck ramp so that trailers may be docked at any floor (see pic). This does claim more land area, which must be recovered from above, and doesn't work well if trucks have to shuttle between multiple floors.
- While both Singapore and Hong-Kong act as hubs, Singapore is much more international, receiving goods from manufacturers all over Asia and shipping it to other countries; Hong-Kong receives mainly Chinese goods. Also, for the latter, many of the goods come in via trains and trucks, while leaving by ship or flight, while for Singapore it comes and leaves via sea and air.
South and Central America
- Labor costs are low, though not as low as in China, and the nature of its local economy and customers does not justify high equipment expenditure.
- The only exception is Mexico, which can quickly ship products to the US and keep its inventory low, thus justifying state-of-the-art technology.
Final thoughts
Some general conclusions can be drawn.
- Labour costs are a factor when considering automation; automation is a factor when considering optimisation; optimisation is a worthwhile expenditure when dealing with high value goods with a high velocity.
- Cheap land seems a fundamental advantage, looking at the logistical nightmares that Singapore and other high-rise builders must be experiencing.
- Access by land will significantly decrease the cost of transport. Generally, a well-developed infrastructure means more access to wealthy markets and enables warehouses to store high-value/high velocity goods, which is good for them.
The book 'WAREHOUSE & DISTRIBUTION SCIENCE,' which is available as a free download, provides some incredibly detailed info on how to effectively set up warehouses and distribution chains. Well worth a glimpse, if not more.
 Let's face it, even with nature knocking on our door, some accountant will still ask what this whole thing is going to cost. Science, facts, morality… it's not enough. I compare it to smoking; even though everyone knows smoking kills, it took pressure—social, governmental, commercial—for people to quit. And the same applies to businesses going green.
Without further ado, here's five pressures that make the business-case for companies to change.
1. Governmental pressure - let's ignore for a fact that government is the one keeping its finger on the pulse of scientific research, social, business, and technological trends. But what is hard to ignore is that the government is actively pushing businesses to change, either by punishing the wrong-doers, by subsidising clean practices and technologies, or by providing new infrastructures around these new rules, allowing for businesses to dispose of their waste in better ways and use alternative, cleaner energy-sources.
2. Consumer pressure - like with smoking, not all consumers have been following the new green "religion" quite as passionately. That said, there are the early adopters, the geeks, the pressure-groups, that are insisting on businesses changing their ways. And those businesses are themselves customers to their suppliers and are doing the same thing to them.
3. Business climate pressure - apart from the above, two things will strongly pressure businesses to change: costs and competition. The rising cost of fuel, electricity, and water, etc., as well as the cost of disposing their waste, is a good incentive to implement technologies that help conserve energy and produce less waste. Similarly, as competition will do the same, businesses are forced to respond.
4. Knowledge-carriers - with the amount of scientific research being produced everyday, it was only a matter of time before methodologies would be developed to help businesses become greener. Since this is still a specialised activity, both commercial parties (consultants) and governmental institutions are there to advise companies on how to change.
5. New technologies - new inventions are constantly being brought to the market, that help businesses conserve energy or get it from alternative sources. Think: technology to monitor and regulate energy-use, water-conserving toilets, more efficient lights, green roofs, etc.
Anything I missed?
In a way, you can't blame businesses for resisting. There have been lot's of change-initiatives these last decades—from ERP to joint ventures—which have produced questionable, if not disastrous results. For change to happen, it must be driven by strategy first, because doing business is like doing war. There is a high price for failure and no one will be congratulating the loser.
But what is certain, is that eventually there will be no more choice. Those that are slow to react will do so at the cost of an unsympathetic government, of the competition racing ahead, and of customers dropping their support.
This article is mirror-posted on tech IT easy, where there's also an interesting discussion going on. Why do people end up going green?
Just some finishing up on the IKEA-book. Following graph describes the structure of IKEA's business, as far as I understand it. 
1: Stores - The way the company expands horizontally, is through a tightly controlled franchising system. This both saves costs and minimises international risks.
2: Sales & service - the company is tightly integrates its sales- and service-operations with customers, the latter taking over 80% of the work (and loving it). Huge cost-savings, also benefiting customers.
3: Supply, manufacturing, design - The company is equally well-integrated back up the value chain, with suppliers, manufacturing, and design, and has—since the 90s—been expanding its operations in that direction. Some cost-savings by introducing savings up the logistics-chain, and more flexibility in manufacturing.
4: Management structure - non-public virtual entity that licenses the IKEA brand and is able to offset international tax-differences by being located in Belgium/the Netherlands and changing the terms of licensing-agreement as needed.
You can draw your own conclusions from that, together with what I've written before.
Things that stuck out from the book included:
- Ingvar Kamprad, the founder, who has both a trader's mentality and is at the same time a community-person;
- Sweden, IKEA's country of origin, whose restrictive tax policies actually resulted in pushing the business to become a global company;
- IKEA's cost-philosophy, which is very frugal and part of the company-culture, and also transmitted to the supply side and to customers. Some problems retaining top-employees as wages are not competitive;
- Its franchising-system, which somewhat surprised me, can be explained by the scientific way in which IKEA's operations has been built up. The more rational, the "easier" (a relative term) to replicate. It's also in line with the business's rapid global expansion and its drive to push down costs;
- It's a private company, which makes it less visible and (relatively) less accountable to the public.
- Its vertical integration with suppliers and customers, enabling it to quickly respond to new trends and problems, as well as introduce higher cost-savings than its competition.
P.S. I'll be taking a few days off, to recharge some creative energy.
What's the biggest pain in your industry II - Carbon emissions
0 comments Posted by Unknown at 11:17 AMContinuing from part I - obesity, this post will be equally light as I have "♫ my mind on my money and my money on my mind… ♫" Or something to that effect.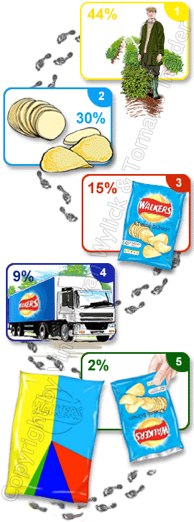 According to a carbon-emission calculation of PepsiCo's Walkers crisps, the majority of carbon emissions come from the production of raw materials (44%) and processing thereof (30%). A Dutch magazine, Tijdschrift voor Marketing, attributes the majority of the carbon footprint to transportation of said materials, and forms the conclusion that more and more production and consumption has to happen on a localised scale.
Even though the makeup of those figures may be open to interpretation—there is no breakdown about what in the first 44% is due to actual farming and what to transportation—perhaps, Mr. Kuiper, the author of that piece, has a point.
In a TED-lecture, James Howard Kunstler argues that the 'hydrogen-economy' is a pipe-dream and we must start thinking about creating urban environments fully equipped with the means of production, transportation, living, and waste-disposal, all in one. Very inspiring, though clearly requiring significant paradigm- and resource-shifts from today's globalised economy.
Clearly transportation comes at a cost, the question is how much the alternative would cost. Building super-farms, creating artificial climates to grow exotic food, waste-disposal, dealing with virus-outbreaks—regarding the latter, farmers already have problems dealing with chickens, sheep, and cows now, let alone having to deal with something like Kunstler's utopian vision—all of which represent costs that have to be accounted for.
But, I don't want to sound like a pessimist. I actually love the idea of a super-farm and a super-urban environment, regardless of the monetary cost. I'm sure plenty a sci-fi artist has tried to draw such a very thing (as have I). It's complicated, expensive, but exciting at the same time.
Asking you a tough question: How would you do it? What would a Kunstler-inspired localised economy look like to you? Is it even possible? … well, something to think about anyway…
Premise of this post: I'm going to get my camera fixed, for the second time in 3 weeks, at a store called Saturn. It is, as far as I know, the only other German chain focussed on consumer-electronics in the Netherlands, next to Media Markt, which is clearly the no. 1 here and in Germany. Ironically, while they appear as competitors to the consumer, they are owned by the same concern, Metro Group.
Now, I don't know the exact reason behind internal store-competition. The only company I worked for, where something like this was the case, was Sony, who allocated annual budgets to individual departments based on their performance. Reminds me a lot of the way governments are run. Of course, bureaucrats have a job for life.
While I was at Sony, I've never seen so many departments closed and managers fired, and both physical locations where I worked in Germany & the Netherlands, are no longer in existence. To a large part, in my opinion, this explains the troubles that Sony is in today, many of which are a disconnect with its audience and, very likely, caused by disconnects within the gigantic company also. But… that's a story for another day.
The other area where I know about examples of internal competitions, are product-lines. Didn't Steve Jobs once say (paraphrased): "If anyone should take marketshare away from one of our products, it should be Apple." I think that this is a conscious decision of Apple and I briefly touched upon it at Tech IT Easy, in regards to form-factor of the Macbook Air (MBA)—the screen, hard-drive, and CPU, which very much overlap with (read: fit into) other products that Apple sells, and, to me, represent economies of scope and scale to the company. It doesn't matter if the MBA sells or doesn't, what matters is that component costs will go down and innovation will go up, which is good for Apple.
Now, none of this really answers the questions why Saturn and Media Markt occupy the same market-segment. And, I have to confess, I just opened my Retail Marketing book to find the answer, and couldn't find it (the book is apparently not focussed on business strategy much).
Both Media Mark & Saturn offer similar features to customers, which are mostly represented on the chart below: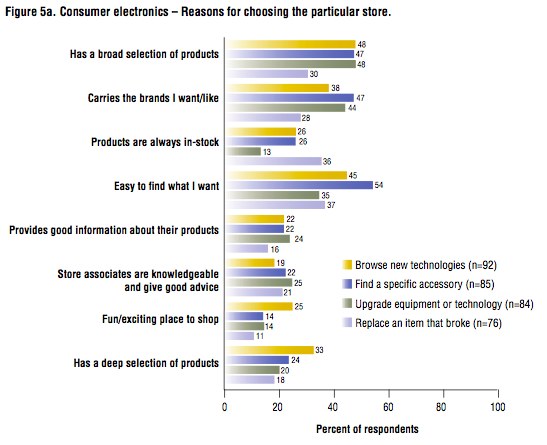
(Source: IBM white paper - "Deeper Customer Insight," which I wrote about several times before)
Some differences are perhaps that Saturn was most often located within another Metro Group-owned store, called Galeria Kaufhof, though I think they are changing that strategy in Germany, and certainly in the Netherlands, where they are stand-alone. Media Markt, as far as I know, has always been stand-alone. Both facilities are rather large, offer parking-facilities, and are usually located within the city (though in Rotterdam, Media Markt takes a more prominent place). And prices, promotions, and brands, while similar, differ in certain areas.
From this, I think it's safe to conclude that market-saturation is a clear goal of Metro-Group. By giving customers not one, but two large options, with separate deals to be had, at separate locations, etc., it appeals to an implicit customer-demand, that of choice, and takes attention away from other, "lesser," and certainly not Metro Group-owned choices.
Something else that is interesting, is mentioned on both companies' websites. Both chains are very decentralised in their management-structure. Every store acts as a self-sufficient enterprise, co-owned by each director, who, with his/her team, is responsible for how the store is run, and ultimately, how successful it is. Kind of sounds like a franchise.
So, I can only conclude that the internal competition paradigm is very much similar to that of Sony's, to force individual stores to perform better.
I think it's an interesting strategy and clearly Metro-Group is the winner here. How this plays out for individual stores and their share-holding directors is uncertain and clearly depends on the skill-level of store-management and the level of support given by their parent-company.
 I'm spending a lot of time with a friend this week, who runs a start-up in a developing (2nd world) country in the lifestyle-food sector. I won't mention his name, his company or focus, or his country, nor anything confidential, because I don't want the information to be used against him. Instead, I'll talk about some general principles, that I've identified.
The irrelevance of business-literature
We both studied at Rotterdam school of management (sometimes known as Erasmus), and spent some time there last night. Funnily, I came across an article in a university-published journal identifying 6 traits of leadership to ask for in the "new" workforce. Keywords included: ethics, diversity, global outlook, tech savvy, adaptive capacity, and the X-factor (charisma?). I asked him, as a joke, which he thought applied to him. Global and adaptive, he responded. The rest meant virtually nothing to him. As a start-up, I guess, you have to do what you have to do, to stay alive.
The advantages of 2nd world start-ups
I distinguish between 1st world (e.g. the Netherlands), 2nd world (e.g. Brazil), and 3rd world (e.g. a large part of Africa), when I look at countries. 1st world countries are mature in their development, 2n world countries are not yet mature, but their economies are growing pretty fast, and 3rd world… well, I'm pretty depressed about that, though sometimes there's surprising pockets of entrepreneurship and innovation.
The advantage of a fast growing economy is that people are still figuring stuff out, meaning there are a lot of inefficiencies and gaps in the market. Another advantage, in his country's case, is the interests of governments in boosting those economies. If your innovative, the grants you receive may be both easier to get and larger in size than anything available in 1st world countries.
For start-ups, another advantage is that you can look at what works in a 1st world country and use that for your own business. This principle is not exclusive to start-ups, it's also relevant to the innovation race between Europe and the US, for instance.
The costs of educating a market
My friend operates a lifestyle-food start-up, as I said. One gap in 2nd world markets is usually that that segment is underdeveloped. But, if the economy is booming, wealth is increasing, and that certainly has a positive effect on the luxury-market.
However, when you introduce a new product to a market, you'll have to build the market up first. There are various approaches to marketing, I'll just go into the one that my friend used.
Essentially, you want to get your products into a supermarket, and you want people to buy the food. Sometimes one, sometimes both will take some convincing. In the beginning. he spent a lot of time in supermarkets, getting people to taste his food. After that went well, he could use that success to convince other supermarkets to become customers also.
Two advantages of supermarkets: they usually have pre-written contracts for suppliers so you don't have to draft them yourself. And they sometimes operate in chains, which makes it easier to get larger customers.
There's two further things to do with food, to make customer-adoption a little easier. One is to sell it in an easily digestible fashion, e.g. a snack. Two is to not do so, and instead provide customers with instructions to prepare the food. You could do this on the packaging, a website, and even more drastically (can't mention what). My friend is pretty active in this area.
Another problem with 2nd world countries is that, while your food may be part of a lifestyle in the 1st world, it's close to impossible to lead that lifestyle over there, because all the components are not there yet. So, in fact, you don't use that lifestyle as a marketing-term. Instead, focus on health-advantages, as that is often the underlying driver for such demand.
Still, even after more than a year, my friend spends about half of his monthly expenditure on marketing—which goes through a marketing-agency that designs the brand, the colours, etc.
Global outlook?
As a start-up, you have to work within certain boundaries: limited money, staff, production-facilities, time, etc.
The clients for a food-company may very well be supermarkets, which, as I mentioned, have the ability to buy a lot. My friend is expanding into other countries, but he's carefully picking the ones that don't exceed his capabilities.
He prefers a fragmented market, where he can concentrate on a one or two chains at a time, not a market where there's national chains that could bleed him dry.
Related to this, fragmented markets are usually underdeveloped also, so in fact he is exporting to countries similar to his own. That, at least, is as theoretically expected.
Theory, schmeory.
While there are certainly concepts that can be found in a number of different fields, ranging from entrepreneurship & strategy, innovation, supply-chain management, and marketing, it remains a matter of being practical, and specific to the business.
Entrepreneurship is a 60-80 hour / week job, usually. You don't have time to check out business-journals, etc. to do your job.
P.S. his business-plan was 2 pages long.
And those… are the facts of life. More, if I can think of it. The picture is completely unrelated to his product.
- For Technology, it's arguably Waste-disposal (I'll be writing about this soon on TechITEasy)
- For Media, it's finding a Business-model to compete with free.
- For Food, I would say it's O B E S I T Y.
And yes, I'm back! My 180-page thesis (or 135 at font-size 9) is being checked, and I'm in Rotterdam picking up the pieces of my life and making a delicious milkshake… whoops, I meant a yoghurt-smoothy… gotta watch that diet !!!
 Hello,
In this piece, I am planning to discuss my current thoughts about my thesis, this blog, and my plans for the future.
I suppose, to a great degree I like to be a focussed person. I like to have goals, pursue them, and not get too distracted by things. It's kind of a silly attitude, because life is an exercise in overcoming distractions. As Fred Wilson wrote recently about something that Dick Costolo, co-founder of FeedBurner, said:
"A startup is the process of going down lots of dark alleys only to find that they are dead ends. The art of a successful deal is figuring out that they are dead ends quickly and trying another and another until you find the one paved with gold."I love that quote and I think it's a great attitude in life as well.
But, as I said, I love planting myself behind a project and shutting the door to everything else. I tried doing this here, 8 days ago, and, as a result, underwent a pretty amazing productive period since then. So what are my plans for my thesis?
My thesis on funding high-tech start-ups
As I said, 12 days break, which would give me another 4 days. Truth be told, I have to add writing a conclusion, writing mini-summaries per chapter, an executive summary, and editing the whole thing into the mix, so I will like likely be busy for another 10 days after that. The nice thing about conclusions is that they are already in your head, summaries happen automatically as you edit a piece, and editing is a perfect all-nighter activity.
The not-so-nice part is that we are currently at 150 pages of material, which would more or less make my thesis a book about innovation, entrepreneurship, venture capital, and incubators.
2 thoughts:
- One of my thoughts is to edit it down to a reasonable size and publish the whole thing as a pdf.
- A second thought is that as I write summaries per chapter, I might as well turn them into blogposts about innovation, entrepreneurship, finance, and incubators, and publish them in the form of regular blogposts on Tech IT Easy.
Which brings me to this blog…
The status of (my blog on) sounds + food and retail
The funny thing about this blog is that it is interconnected with my life. Random readers may think this is a nice (or not so nice) blog about subjects concerning music, food, and retail, but it is in fact, what I see as, one of several stages towards forming a career and a business (or series of) in this industry.
So my head has not stopped thinking about this subject, and I've actually been making summaries about interesting topics, and thinking about the shape of things to come. I cannot interrupt this blog too long, at the same time it is reassuring (to me), that even though my publishing took a break, my mind did not.
Concerning this blog then, I will be back and I already have a huge backlog of material to publish here… looking forward to that!
The status of "real life"
As I speak with friends and strangers about my ideas I also realise that there is much that remains to be done in "real life" also. I believe everything starts with a good business-plan with realistic assumptions about what you want to set up. It is the ultimate "social object" towards getting my plans in motion, convincing partners, investors, employees to work with me.
Questions I have received so far include:
- What type of place do you want to set up? My answer has so far been: probably a night-venue, a restaurant or night-club, or something in between (this may come as a surprise to some of my readers, as I write a lot about retail). Ultimately though, I want to set up a successful venue and am flexible on the format.
- Where do you want to set it up? My answer: I'm flexible, but it depends on where I feel most comfortable to set it up.
- How are you going to fund it? My answer: I'll need to save a bit, but I expect my first business to be sponsored, probably over 50%, and will look for suitable working partners also.
- When do you want to set it up? My answer: 3-5 years from now would a realistic number in my mind.
- When do you want to exit? My answer: Depends on how much fun I am having, as well as other factors. I see myself as both a serial entrepreneur and someone who wants to create great things, and I'll have to find the middle-path between both.
Final thoughts
First thing first. Finish my current project, get a degree, close this chapter of my life.
Intermediary thing, publish blog-posts when I can and want to, in between.
Afterwards, blog more, look for a cool job to gain experience, contacts, and cash. I also want to travel for a bit through Europe to decide on a suitable location, check out different formats, and brainstorm with friends.
And then, take the plunge.
So, à bientôt, I hope!
Vincent
 A few months ago, I wrote about Starbucks' vertically integrated strategy. This morning, i wanted to link to it, so I did a Google Blog-search. Usually a search for Starbucks and "vertical integration" would yield my blogpost first, but now it's the no. 2 result.
Somehow, the net has started discussing why Starbucks had a corporate strategy that involved owning all of its subsidiaries and Subway's strategy went a different way.
There seem to be a number of theories on the market. Namely that Starbucks
- … cares less about cross-store cannibalization
- … has a higher need for monitoring
- … relies more on “impulse sales”
- … has higher profit-margins
Some good posts about this are written here and here (both by Josh Wright), here (Stephen Bainbridge), here (Keith Sharfman), and here (Paul Jaminet)
All excellent theories in their own right, and all very rational. However, in my experience, people, and we are talking about people here, often don't behave rationally (at least not as rationally as economic theory dictates). Instead they behave in ways that they are able—either through innate capability or through their environment.
Starbucks did not start as retailer, it did not even start as a store owned by Howard Schultz. It was a coffee-bean roaster and vendor. Its aim was to educate the US-population, which was—according to Schultz—a wide open market in terms of high-quality coffee. Schultz, who first worked there as an employee, started an independant coffee-chain, and only a few years later took over the Starbucks-business (incl. the roasting factory) and the brand-name. But the core-idea remained that it had to deliver quality-products and quality-education to its customers. Along with this, Schultz was highly educated, had plenty of work-experience, and venture capital behind him.
Subway started as a retailer. According to the history, published on their site, Fred DeLuca started Subway's as a 17 year-old and $1,000 starting-capital. Subway had, as far as I know, no world-changing mission. It was a sandwich-store, one of many, and one of it's key assets was to be more efficient and qualitatively better than its competition.
I still think that the stories of these two men, their business-idea, and the environment they started it in, is the key-deciding factor of why one decided to expand wholly-owned and the other through franchising. I haven't studied Subway, but I have McDonald's, and the same dynamic can be witnessed there.
Now, you can go all "economic theory" on this, and focus on points like that coffee is a product that requires much more monitoring than sandwich-ingredients. And I think that's completely correct. Not to mention that Starbucks has a very different employee-based strategy than Subway—they like theirs to be smart and pay them well. And I also think that due to Starbucks's high real-estate presence, franchising for them has become an unfeasible solution. But I think the first two factors are the cause and the latter is the consequence of Starbucks's wholly-owned strategy.
When you start out, whether to franchise or not is a completely personal decision. It comes down to how comfortable you feel about whether you can offer your customers the highest quality possible, while maintaining healthy economic growth.
And your initial decisions will clearly have some kind of lock-in effect later on, which is something I only realised after reading the linked-to blogposts and writing my own.
Essentially private labels, also sometimes called house brands, are products branded either with the name of the retailer, or, at times, sharing some kind of umbrella-name, decided by the distributor or otherwise. But what private labels really represent, to me, is the ultimate example of a power-struggle between a retailer and suppliers. Sometimes, but not always, it also means that some kind of vertical integration has been taking place between retailers and manufacturers, or, at the very least, packaging plants.
For now, I'll just be looking at some stats on private labels. At a later date, I'll take a look at more supplier-retailers dynamics, branding strategies, etc.
Geographic share
According to an ACNielsen report (pdf), the global* market-share for private brands was 17% in 2005 (* global meaning 38 countries and 80 categories), and had grown 6% that year.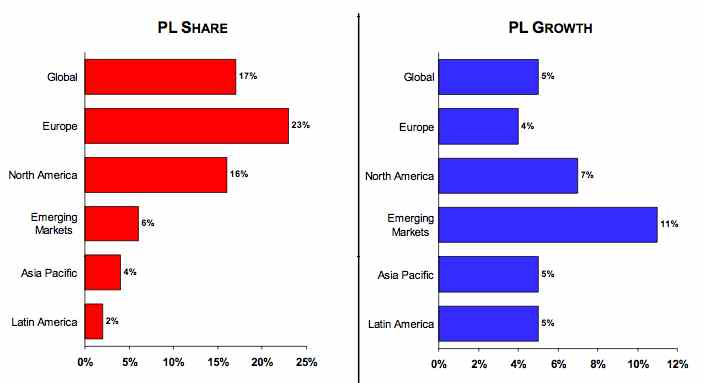
Figure 1: Share & growth rates of private label by region (based on value sales) (source: ACNielsen, 2005)
Europe has the largest market-share with 23%, and Latin America the smallest, with 2%. Top countries included Switzerland, with 45%, Germany, with 30%, and the UK, with 28%. The largest Private Label growth happened, unsurprisingly, in emerging markets (11%) like Croatia (77%), Greece (24%), and Thailand (18%).
One big growth-contributor in Europe is the strong growth of hard discounters, such as Aldi or Lidl (both German chains), who are present in every European country and expanding rapidly. With Aldi, for instance, private labels make up 95% of sales.
Private label foods
Category-wise, refrigerated foods have the largest overall share of private labels, namely 32%. Complete ready meals take the lead here, with an average of 47% private label-share. In the UK, 97% of ready-meal sales are in fact private label.
Another significant private label food, or rather drink, was milk, of which private labels make up 43% of sales.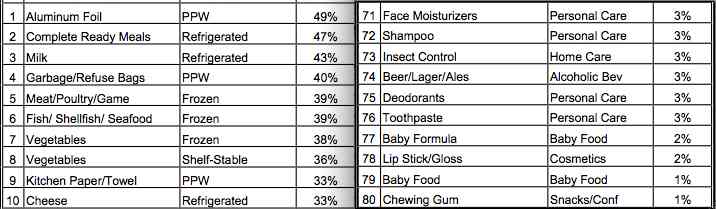
Figure 2: Value shares of private label by category (source: ACNielsen, 2005)
Other high private label food-products include frozen meat (39%), fish (39%), and vegetables (38%), and 37% for shelved vegetables. Frozen pizza is at number 27, with 17%, tea and coffee at numbers 37 and 38, with 14% and 13% respectively. Wine is at number 44, with 12%. And Beer is all the way at the bottom, at number 74 with 3% !
Among the fastest growing foods are drinking yoghurt (28% growth), baby food (20%), chocolate (13%), and water (13%).
Pricing trends
One of the strengths of private labels is of course that they are cheaper, on average 31% less than manufacturer brands. Emerging markets showed the biggest discount, with PL-goods costing 41% less on average. Europe wasn't lagging in this respect either, with an average price difference of -37%. On a country level, Greece, Australia, and Germany were taking the lead with, respectively, -48%, -47%, and -46% discounts (compared to manufacturer brands).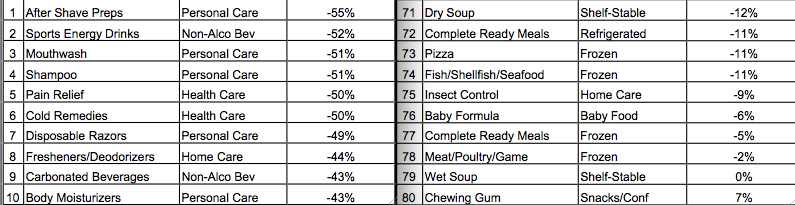
Figure 3: Price differential of private label by category (source: ACNielsen, 2005)
Again, concentrating on food-categories, the products that received the biggest discounts were Sports Energy Drinks (-55%), carbonated beverages (-43%), cereals (-40%), wine (-38%), and tea (-37%). Food-categories taking the least in discounts, included chewing gum (+7%), wet soup (no difference), meat (-2%), and ready meals (-5% <- I guess that explains their high market-share).
Final thoughts
That market share is increasing more quickly in emerging countries is not surprising. Retailers there will likely not be mature and/or consolidated enough to focus on such a strategy, but this is clearly changing.
Germany's dominance is also interesting, as both Aldi and Lidl originate from there. One of my next posts will be on Ikea's European growth and Germany's also very strong there, which suggests a certain preference for low prices with German customers.
Switzerland is still somewhat of an enigma, but I'll try to find out more about it.
In terms of products, both the dominance of private labels amongst ready-made meals, and that their prices are quite similar to regular brands, is very interesting. It could suggest that customers either don't care much for quality and brand-differentiation in that sector, or that private label brands are actually quite good. The price-level would suggest the latter conclusion.
Generally speaking, refrigerated goods are different in the eyes of consumers, I think, less scrutinised perhaps, and worthy of more investigation. Milk is of course similar to water, and hence not really a product where brand makes a huge difference.
What else? Certain beverages, like coffee, wine, and beer are quite interesting, as their private label share is quite low. This would suggest a high brand-sensitivity in these sectors. The low percentage for beer (3%) is certainly striking.
More on private labels as I come to it.
Let's start with a brief disclaimer: I am not a lawyer, fiscal expert, EU expert, or anything that can constitute an authority in matters of European legislation. I have linked to relevant data at the end of this article, which I strongly encourage interested readers to check out.
SEPA, meaning “Single Euro Payments Area,” is an initiative, due to be launched in 2008 and fully implemented by 2010, but has been in the planning ever since the EURO-currency was unleashed upon the member-countries in 2002.
Essentially, while the EURO brought some transparency to consumers, banks, and businesses on a cash-level, SEPA is meant to be the non-cash equivalent, introducing a common standard of non-cash transfers between banks, businesses, and consumers across the EU-region. This is facilitated by a standard referred to as "straight-through processing" (STP), which allows for an automated processing of payments between banks.
Technically speaking, this means that payment-messages between parties will contain certain data-elements that include information on the amount, bank account details and the names of the sender and receiver, and is exchanged between banks through a common ISO-standard, called: UNIFI (ISO 20022) XML.
All of this mumbo-jumbo is governed by the European Payments Council (EPC) (see pic below), which is the decision making and coordination body of the European banking industry in relation to payments, and consists of 67 members, including banks and banking associations.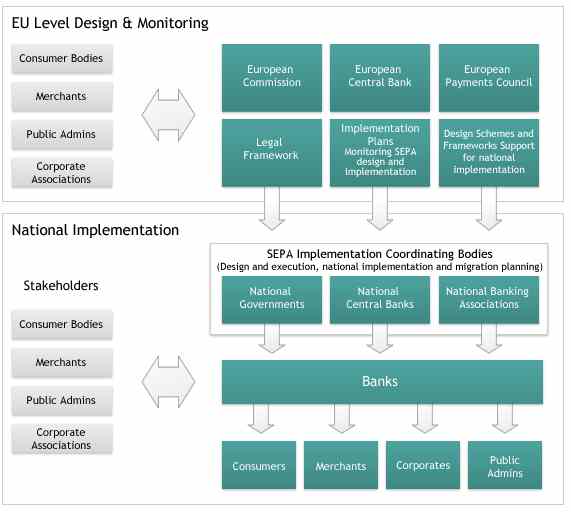
(click picture for more detail)
Benefits to consumers and businesses
These are manifold. Essentially, a harmonised standard allows consumers to easily, transparently, and securely make payments across borders, which also means that consumers don't need to open separate banks to handle their business in different European countries. In addition to this, it introduces a common standard for pension-transfers across banks (and I assume countries), and greatly increases the choice of financial service providers to consumers.
For businesses, the benefits are far more numerous. Essentially, having shared standards allows them to easily accept and process payments from any card from a SEPA-bank. National borders no longer need to be a barrier to growth and businesses can have a more direct financial relationship with consumers across the Euro-region. Similarly, B2B-transactions across borders enjoy similar "upgrades" and will require much less overhead, be more transparent, secure, and quicker than before.
For a more exhaustive list of changes, please check the EPC-report on Making SEPA a reality!
Final thoughts
While this all sounds very rosy-coloured, I expect that the key-factor will be marketing, i.e. communication about what SEPA is and how to use it. So far, there has been very little news on SEPA, even though it is due to be launched in less than 3 months from now. Similarly, a status-report by the EPC (pdf) points out that there has been very little communication from public authorities about their intention of using SEPA products, and another Dutch article, from a few days ago, reports that 92% of Dutch business-owners are not yet prepared for SEPA.
That said, if anything was needed after the EURO was introduced, it was increased transparency of financial services, and preferably on a pan-European level. Both the fact that businesses and consumers can run their financial affairs from a single bank in a single country, and that both also have more choice of service providers, is a huge improvement. For the latter, I hope the increased competition will lead to more efficient financial services. And for the first, I hope it will lead to more businesses expanding their operations across national borders, and more migration by European citizens across the continent.
Of course, much remains to be done before we can truly call Europe one "country," including a more harmonised patenting-standard, and of course overcoming many of the legal and cultural barriers which continue to exist. But the SEPA, if all goes according to plan, is a significant step ahead towards making this a reality.
Some helpful links
- The European Central Bank on SEPA
- The European Payments Council on SEPA
- EPC-report on Making SEPA a reality (very good to read!)
- Latest SEPA status-report
This is part I of my coverage on IKEA's growth, based on my reading of the book "The 11 secrets of IKEA" (more on this at the end of this article). You can read a previous blogpost on IKEA's "strange alien values" here. I'll continue this series as follows. Starting with Scandinavia, I'll go into how Ikea grew in this area. I'll then continue with Europe, and finally finish with the giants, the USA, China, and Russia.
 Some years ago, I worked on a project where we would try to find out how businesses expanded internationally. In this case, we looked at the tire-industry, and three companies, Bridgestone, Goodyear, and Michelin, and dug through tons of annual reports and news-releases to understand where, when, how, and why these companies expanded beyond their national borders.
The reasons these three companies make such an excellent case-study, is that they all originated from different continents and thus reflect different cultures. It is nearly an unwritten rule that US-companies perceive the world as a single market and make little effort to adapt to local conditions; that Japanese companies are very hierarchical in their structure; and that European companies, as a consequence of the cocktail that is Europe, internationalise quite quickly (or not at all). And for all international activities, it is another soft rule that they would expand to countries with some cultural, legal, and linguistic similarities first.
IKEA is of course a European firm, or rather, a Swedish one, and a preliminary conclusion would be that it would internationalise quite quickly also, yet starting in Scandinavia, then the rest of Europe, then the world. Another assumption would be that it would thread carefully (read: slowly or not at all) in areas which reflected alien values (to IKEA). As will be shown, this did indeed happen.
Ingvar Kamprad and Sweden
A business usually has different components, many of which reflect the values of the founder, and again the values of the society he or she grows up in. IKEA's founder, Ingvar Kamprad, was born in 1926, on a small farm in Sweden. He respected the feeling of community he experienced there. His grandmother, who had migrated from Germany at the end of the 19th century, taught him the value of hard work and encouraged his entrepreneurial spirit.
Ingvar Kamprad had started IKEA as an import-export business, and much of the way IKEA would be run would reflect that idea. When you're a trader, the idea is that the product doesn't matter and to be as efficient as possible (a modern-day example: eBay). In order to save costs, IKEA tried to get preferential treatment with its suppliers, started with selling products via mail-order, and ultimately set up a storefront, which was actually just a warehouse.
Of course, Sweden itself, with its strong socialist values, had a large degree of influence in the way IKEA took shape. Internally, the business was run quite informally, and in many ways reflected the communal environment where Ingvar Kamprad had grown up in. Similarly, the business of IKEA was not meant to be elitist, rather aimed at middle-class families, a large component of Swedish society. Sweden also had a long tradition in furniture and design and that was another influential factor.
IKEA
IKEA was set up in 1943, already a successful mail-order business, and soon after Kamprad would start a business-degree to learn the theory of distribution. After some years of studying, working for other businesses, and finally military service, IKEA's first employee was hired in 1948. This was also the year that Kamprad decided he wanted to make IKEA big and to that effect, started a folder-campaign via a regional newspaper.
The competition in this business was tough, however, plenty of mail-order-businesses in Sweden, and the competitive landscape orientated itself around lowering prices. A natural consequence was that the quality of products also went down. Because Kamprad was made aware of this through countless letters from customers, he came up with the idea of having customers check the products themselves, which is how IKEA, the store, was born.
Two features were important here, one was that the primary way to order was still the catalogue, and the store a complementary service. And two, the self-assembled furniture, which grew out of the need to ship products more safely. This also brought a new degree of involvement by IKEA with their suppliers, essentially bringing innovation upstream, which help suppliers to save costs, and downstream, as self-assembly became a large cost-saver for customers also.
At the same time, IKEA's new retail-focus brought in a new level of competition, that of other furniture-retailers. Afraid of the popular and far cheaper business-model of Kamprad's, and angry at the obvious copying of designs that IKEA was doing also, these retailers started pressuring local suppliers to no longer work with IKEA. This forced Kamprad to use some questionable business-practices, such as starting anonymous daughter-companies to deal with these suppliers, amongst others. In the end, it also lead to him to having to look abroad for new suppliers, which I will write more extensively about in following blogposts.
Noteworthy was that before expanding to the Swedish capital, Stockholm, IKEA had already opened an outlet in Oslo, Norway's capital, in 1963. Two years later, the first IKEA was opened in Stockholm, which turned out to be a massive success. IKEA was well-fitted for the times also. The Swedish socialist government had implemented an ambitious plan for urbanisation, which involved building a million houses between 1965 - 75. Since IKEA was well-able to meet the booming demand for cheap furniture, this was a match made in heaven.
In 1971, IKEA unleashed another innovation. A restaurant, which served food to the clientele at affordable prices. This was another way for IKEA to become a lifestyle-trendsetter, and also started the urban legend that meatballs were Swedish (IKEA's recipe was actually British).
Scandinavia
While IKEA was already established in Norway, and had suppliers in Denmark, it opened its first retail outlet there also, in 1969. Towards the end of the 70s, there were altogether 6 different IKEA-stores in the rest of Scandinavia. All of which were personally owned by Ingvar Kamprad.
It was not long after, 1973, that he and his family also moved to Denmark, to flee the insane taxation-system in Sweden, which I explained in my last post.
Final thoughts
Clearly, much of what made IKEA successful world-wide, started with innovations introduced in Sweden. IKEA's mail-order- and warehouse-model, its close integration with suppliers, its focus on providing cheap lifestyle products, and also its internal frugality—which I did not speak of, but IKEA-employees are traditionally paid below market-value. All of which fits with my philosophy of "where you are from and when you are from matters a great deal to where you are going."
IKEA's international expansion started with Scandinavia, which was a region with a lot of cultural similarities to Sweden. As I will explain later, this is a trend that would continue in Europe also. At the same time, the reason that IKEA expanded internationally, could also in large part be explained by the competitive pressures inland—IKEA's troublesome relationship with Swedish suppliers—and with the socialist regime, which was largely incompatible with running a profitable business, and forced Ingvar Kamprad to look elsewhere for a more business-friendly environment. This was also the philosophy, when expanding into Europe, which I describe in a future post.
All in all, IKEA makes an interesting case-study, because it is a European business, and it is interesting to see which of its values were compatible with other countries and which countries presented more difficulty and why. Much more on this in future posts.
The book "The 11 secrets of IKEA" is sadly not available in English. If you do read Dutch, I do recommend picking the book up here, and for German, check the German Amazon-store here. For other book-reviews, check out my look at eBay's "The Perfect Store" here, McDonalds "Grinding It Out" here and here, as well as at Starbucks' "Pour Your Heart Into It" here and here. The picture is courtesy of Culinaryartsblog.com

 The


