 The world of business, I think, has a certain illogical—the "human element"—shell around it, but centres around the concept of supply and demand. How you create a business where demand is high, how to you make sure that you have sufficient supply and/or not too much supply. You can see this play out in a number of places, e.g. on the web you have scaling issues, when your service proves to popular (e.g. Twitter), or you have the case of the million+ blogs that are collecting dust, because no-one ever reads them, or because the blogger was unable to gather enough interesting supply.
In restaurants, or food-places, you also see this play out. A couple of months ago, I was going to write about take-out, how some businesses embrace and others avoid it, and why. I think the reason is, at least in part, to control supply. If you control supply, then you can focus on quality and charge a higher price. You also become an artist/creator, rather than a factory.
How do you limit supply? Two ways, I think. Mainly it's the physical space; by limiting the number of seats in your venue, you ensure that a certain quota is set (of course, the question is also whether that quota is met, which comes from quality inspiring demand). By investing in quality-ingredients, you not only limit your budget, but also your production-capacity, and it forces you to limit supply. That's a little vague, I know, I haven't worked it out 100%.
The other way, is to have an increased level of supply. How do take-out and fast-food places do it? By standardising as much as possible. Whether it's the ingredients, which are mainly starch-based (burgers, pizza, noodles, etc.) and cheap, the production-facility (often just an oven, a grill, or a big wok), or a standardised customer-space (from seats stapled to the floor, to waiting-lines, to a website/phone nr.). All of which enables you to deliver mass quickly.
I was thinking about this today after watching "Iron Man," which is one big Burger King (and US-army) commercial, and getting a cheese burger afterwards. Burger King was packed and, ironically, slow. The "waiting in line" method doesn't seem to work that well when you have 50+ people waiting, and a limited space behind the counter to deliver burgers and stuff. People on both sides were bumping into each other constantly, and I actually had to wait over 5 mins, even though I was second in line.
On some level, I like to think that technology can solve a little bit of this problem. If you look at Zara and H&M, which I wrote about last week, both are very advanced in this area, in order to optimise and speed up their production, logistics, and merchandising. Of course, that's on a back-office level, and that's not the same as the front-office, where customers interact with a business. No one wants to be confronted with a screen to do the ordering, but sometimes I wonder if people wouldn't be happier just pressing some buttons in a fast food joint, rather than waiting in line. Of course that would mean more seats, as more people would sit down, and more staff, as someone will have to bring that food to the table.
In the end, it probably comes down to experimentation and constant improvement. That said, apart from the computers that cashiers operate, and quicker food-preparation, not much has changed in the last 50 years for the people doing the actual eating.
The picture is courtesy of lightningspeed.net.
 Time for a wee break. In the last week, I've been researching Zara and H&M a little, to better understand the retail-sector and the fashion-segment. I'll probably have to do a follow-up to this post, as there is lots to say about both businesses, but here's some initial impressions, nevertheless.
First off, H&M appears a lot more clean in its approach. Judging by the annual reports alone, H&M not only has a 2007-edition (Zara is only up to 2006), but it is also only 85 pages long (presented in an eco-friendly 2-pages-per-side way), while for Zara, or actually Inditex, it's mother-company, the annual report is a stunning 450 page long!
Now, that's really not all that surprising, as Inditex is composed of a number of companies, and it is extremely vertically integrated, while H&M employs the Nike or Apple model—it designs and it retails, but it doesn't produce.
Why this is so, I can only guess, is due to their origins. Inditex comes from Spain, traditionally a low-waged country, while H&M is Swedish, not a low-waged country. Similar to IKEA, I imagine it was an economical decision to outsource most of its supplies.
It's very hard to separate Inditex from Zara, as both are founded and owned by the same person, Amancio Ortega Gaona, Spain's richest man. Zara has been in existence since 1975. H&M was founded by a Swede, Erling Person, in 1947, who ran the company to ca. the mid-90s, but which has continued to be a family firm.
Their business-philosophies are fairly similar, a low-cost, high-quality approach to fashion, as opposed to traditional brands, where quality most often equals price.
Zara made lots of headlines with its extremely high turnover of products—it produces around 11,000 items annually (as oppsed to 2,000-4,000 for other retailers); 15-20% produced before, 50-60% at the start of the season, and the rest during. If a product fails to do well, it is usually removed after a week in stores.
H&M made headlines with its celebrity-marketing, which is noteworthy, as Zara has virtually no marketing. Instead, because it has such a high turn-over of goods, customers tend to visit it more often, expecting new things—an average of 17 times per year vs. 3 times for other stores!
Both employ mostly a wholly-owned retail-strategy, except in countries where this is not possible. And both are very advanced in their use of IT to manage logistics and production, which is definitely seems to be a key-characteristic of delivering fashion quickly and find ways to decrease costs.
H&M's largest markets are Germany, Sweden, the USA, Spain, and the Netherlands (in terms of sales). For Zara it is Spain, France, Germany, and Mexico (in number of stores).
That's all I can think of in 30 mins or less…
 Take a look at this quote, which I posted a few days ago:
"There should be a rule: before helping the environment in one market, we should be required to think through the impacts on other markets." (source: Freakonomics blog).Or, to put it differently, every action has a (sometimes equal) reaction (I think the traditional phrasing ignores the human element). The idea that everything is interconnected is both fun to right-brained generalists like me (not a compliment), and scary at the same time. The global economy is very complex and, I would say, impossible to regulate.
There's a couple of things going on the world, which I'm sure everyone is aware of. There's a number of wars, there's the weakened dollar, there's some kind of housing-related recession going on, there's a shortage of oil, our planet is perceived as suffering and currently being saved (I hope), there's India and China, the rise of the Anglo-Saxon system, etc. etc.
And some of the biggest problems facing the food-industry (depending where you are in the chain), are rising food-prices, which relates to that oil-shortage (both in terms of pricing, but also because of alternative fuels using farm-products), the rise of India and China, and some other factors; and the costs of keeping green, which has largely been inspired by companies like Wal-Mart, but also by the (exaggerated) need for global diversity by customers (which the food-industry is also partially to blame for).
The solutions vary, and are, so far, very defensive in their nature. For the cost of going green, most pollution comes from transport and the solution is to either use the most eco-friendly way to go: on land, by train, across water, by ship; or to go local—which companies like Marqt seem to focus on, but which also comes with the pitfall of seasonal shortage.
For rising food-prices, again one solution is to go local, to save on transport and have some control over how farmers work, and be able to charge higher prices to the rising local-conscious consumer. But a bigger solution is for more food-production to happen (much of it currently goes to India & China, or to biofuels), and possibly from smaller farmers. The problem here is that it will take time (some estimate decades) for smaller farmers to get ready.
Both are definitely big picture-problems, and will take time to solve. One thing, I'm personally looking at, are micro-lending sites like Kiva.org, which put you into contact with local farmers, allowing you to help them out in your own way. From a Venture Voice interview with one of the founders, I understand that some of these investments happen within the context of a community, where each member keeps watch over the other's use and repayment of the funds, in order to ensure a good outcome, and so loans will continue to come in. But, while I think it's well worth the effort, this is still a small-picture solution to a much larger problem.
The way it looks right now, the solutions have to be planned in the long-term and on a large scale. There is definitely space in the farming-segment for more production to happen. In the mean time, food-prices will continue rise, as will the price of educating consumers to make more responsible choices. I like Tesco's approach in labelling the origins of their food and allowing people to make more carbon-friendly (locally focussed) decisions. But that doesn't solve the problem for farmers in remote areas of course.
Sigh, if you just got a headache, I sympathise, as I just got one too.
Further reading:
- NYTimes: Environmental Cost of Shipping Groceries Around the World
- Economist: The new face of hunger
- Buzzfeed: Food Hoarding
Interlude: From medical to space-tech - How technology affects incubation-strategies
0 comments Posted by Unknown at 8:48 AM High-tech… My never-ending hobby! Read about it on Tech IT Easy!
 Read it on Tech IT Easy!
According to Distrifood.nl (Dutch) the " man's cola" showed a nice profit this last year, making it the top new introduction to a brand in 2007.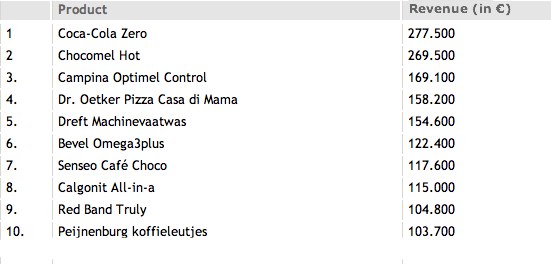
(Source picture: Elsevier.nl (Dutch))
I only point this out, since Coke Zero is one of the first food-related topics I wrote about on Tech IT Easy; a, fairly clear, signal that it was time to "spin-off" to this blog.
 An interesting quote from the Economist this week. Particularly, because I personally suffer from it, and imagine a lot of other people & businesses do too.
Mr. Fellows [CEO of Callaway golfing equipment] believes that the "fundamental principles of running a company don't change just because the product category is different." In his view, Callaway's problems stemmed from the fact that it saw itself as a golf business, not as a consumer-goods company. He resolved to focus on "what the consumer wants, not our own feelings about what the game of golf should be."It doesn't matter if you're the CEO of a company, an investor, a sales-person, a blogger, etc., I think everyone has an idea of what they want and what customers should want. But what it really comes down to is the latter.
Face Value, my favourite section in the Economist, every week.
The picture is courtesy of digitalfreak.net
 When I started this blog, and my general thoughts about the area of food & retail, it was all about the people. A quality staff and happy customers, what more do you want? And I have to say, from past experiences, that I don't really like businesses that don't place people first.
For instance, one individual I worked with, suggested using handicapped people to put together a product manually. I instantly disliked him. Not that I don't want handicapped people to be productive, but it was the thought behind it; to find a "stupid" workforce, which you can save tons of money on. It was just distasteful.
Another company I worked for was very process-orientated.
There's nothing wrong with that of course, but it was a big company with a reputation for innovation and that is why I joined. And you expect such a company to at least push forward a solid project. Well, as it turned out, the organisation's core-strategy was to start a large number of risky projects and have them compete with each-other. Those that would fail would simply be abandoned, and their staff was expected to fall on their swords… metaphorically. The effect was an incredibly high turn-over of employees, all three projects I worked on no longer exist, and it deeply soured my feelings about this company.
Both these examples, to me, represent a lack of respect for the human element. I realise that business is a hard world, but if projects were designed to be solid in the first place, there would be less of a need for these kinds of practices. Just my 2 cents.
Part 2 - the challenges that people businesses face
HBR (Again! I'm sorry, but I read a lot of HBR-articles!) published an article about people businesses some time ago, which I enjoyed. Following are some notes + thoughts about it.
- People businesses are defined as: "operations which are characterised by 1. high overal employee costs, 2. a high ratio of employee costs to capital costs, and 3. limited spending on activities, such as R&D, aimed at generating future revenue."
- In a top-40 list of people-businesses, published in that same article, only a few qualify as food and/or retail related. These are the Hospital Corporation of America, Tenet Healthcare, Marriott hotels, and Accor hotels.
- For instance, a business like McDonalds does not classify as a people business; it has substantial assets in terms of brand & real-estate, and relatively low people-cost.
- People-businesses face a number of challenges, related to performance measurement, people-management, compensation, and business models.
- Measuring productivity is more important in these businesses, then other economic performance indicators, like return on assets or investment. The challenge is finding the right indicators (employee productivity & profitability), as well as benchmarking it against other companies (employee figures do not always need to be made public).
- To manage people, you need to align employees' interests with business objectives & execution. And you need to find ways to measure performance (see above) continuously and see where your weak spots are.
- Compensation is key, as productivity is very sensitive to it, and is a primary determinant of shareholder risks & returns. Other factors to consider are variability—productivity varies across the workforce and how do you get the most out of a diverse workforce—and reach—sometimes the lowest on the ladder are as, if not more important to a firm's performance, and how do you motivate these people to do their jobs as good as possible?
- There are a number of business models are used in these types of businesses: pricing per hour is a safe method, but does not account for extra performance; a fixed price per output allows companies to shave costs off the inputs and thus increase their profit-margins. It is very susceptible to a high-skilled workforce; a success-fee or commission offers the best returns, but also the greatest risks; some companies use a hybrid of these three.
- The strategic weakness with these types of businesses is that your assets are mobile and can walk out the door. By creating value above and beyond your employees, you can diversify some of that risk away. Of course, you could also try to keep your employees ;).
I guess it's up to individual businesses how they want to measure their firm's performance. The most straightforward is certainly return on assets or investment. But even that leads to some question-marks, particularly in today's highly software-based economy, where assets are no longer as necessary, or pricey, as they once were.
For my part, I still think that people are a key-asset to a business, and it's interesting to look at how exactly you motivate a workforce and get the most out of them, as well as how to overcome the challenges related to a people-based business.
Equally interesting is how to align the business-model to match the needs of your assets—the people. Since people are motivated by (financial & non-financial) compensation, do you keep the pay-rate aligned with time-spent; fixed; aligned with performance; or a hybrid of the three? I think the hybrid is always the best choice, but even then some combinations work better than others.
And retaining employees is also an interesting problem; though much less so in countries like France, where getting rid of them is a problem, and differently in places like Silicon Valley, where inter-firm mobility is a key-requirement for many employees. I think the solution is completely personal and cultural, and everybody's answer will be different on this.
The picture is courtesy of prairienet.org
 Just a short tweet.
I'm currently reading a Dutch book on the 2003 crisis at Ahold, but which is actually a historical account of how the corporation came to be. A couple of things I found interesting:
- Ahold actually stands for AH (Albert Heijn) Holdings
- We all know that things are cyclical, but it was interesting to read how a recession and high oil prices were a challenge that Ahold had to face in the 60s-70s, and how they managed to survive.
- In order to inspire Dutch people to shop more, they introduced a financing scheme for fridges, which people couldn't afford at that time. General Motors did a similar thing to help people afford their cars; seems like an interesting way to "upgrade" an economy.
- The fear of a socialist government drove Albert Heijn to look outwards and form Ahold (similar to why IKEA decided to globalise also).
- One of the consequences of politics at that time was the board of directors, meant to provide impartial guidance and represent the workers.
- They made extensive use of consultancies (often McKinsey) whenever they decided on a strategic trajectory.
- One of the directors was a big fan of Harvard Business Review :)
- They use the US as a source of knowledge on how to design their supermarkets. Later on, moving to the US was also seen as a way to increase that learning, as well as a new revenue-source.
- When AH moved to the US, they also brought their own ideas, like, eh, advertising (a terrible, terrible idea).
Entrepreneurial method: believe something is impossible? Enter 'double-think'
0 comments Posted by Unknown at 9:10 AMYesterday, I read an HBR-article by Roger Martin, on his book "The opposable mind", the ability for people to think contradicting thoughts and act on them at the same time (this may sound familiar, if you've ever read 1984).
My first instinct was to throw it out. I didn't like that he used the first few paragraphs to discredit other thinkers on leadership; and I didn't find his proposed method for coming up with a business-model particularly compatible with the general idea of "chaos" that he was proposing (more on that later). I even wrote an impassioned article about it, but waited a day before publishing it (no April fools from me this year). None of my criticism was directed at his core-concept, btw., I do believe in the ability to think contradicting thoughts, and act on them also.
After a night of sleep, I came to the conclusion that Martin's article was effective. Because it required me to think the article had faulty qualities, while the core-idea was right. And that was the very idea of 'double think'! Then I started thinking, what other areas could you apply this to? Pick one!
- My perception of the internet is that it's indiscriminately linear—we forget things the day after they are published. So how could you make it less linear?
- The perception of food is that it doesn't do well in e-commerce—they perish and people value touch. So how can you sell food via the internet?
- My perception of restaurants is that it requires a genius cook, who is both expensive and hard to handle. So how can you start a restaurant without such an individual, or better yet, how can you start a restaurant with one?
Martin's method for coming up a business-model looks like this:
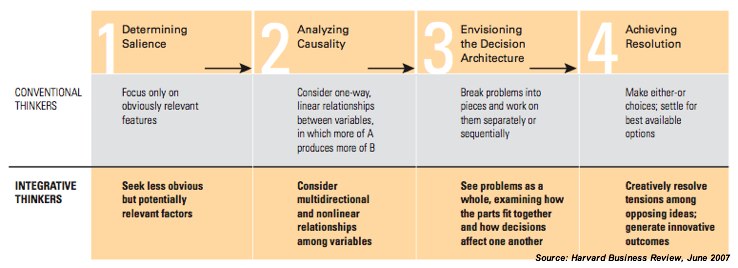
In other words, you need to identify your core-customers, understand that their decision-process is not linear; understand the equally multi-dimensional architecture of your business, industry, and economy; and come out with a product/service that meets these opportunities.
Whether this is the best way to come up with an impossible idea, I'm not sure. But it seems like a logical thing to do after you come up with an idea and are looking to place it within a commercial context.
He uses one example throughout the article, that of Red Hat Linux, which, I completely agree, is one of the best examples to choose. It is free software, but it's a commercial success, which goes against conventional thinking, at least at that time. And instead of just acting as a commodity or becoming proprietary charge-ware, they decided to make a services-company out of it, and a market-leader at that. So how would you turn your open-source product into a commercial success? If that isn't 'double think', I don't know what is.
 The argument for mass-production is that it enables innovations to become cheaper and hence raises the general quality of life of consumers. The argument against mass-production is a more controversial one: that it destroys the unique quality of, let's call it, art.
Starbucks is a very good example of those principles. It brought a higher standard of coffee to the American masses, who, according to Howard Schultz's Starbucks biography, had long been oppressed by low-quality coffee from retailers and coffeeshops alike. At the same time, as the recent crisis at Starbucks illustrates, it has reached a saturation-point: it has brought Starbucks-outlets to every corner in the US, as well as spawned a whole army of competitors, and its brand has become diluted. It has become a commodity.
Back to their roots?
The re-enstatement of Howard Schultz as CEO is a signal, that the business has lost some of its original spirit and is in need of a guiding light. A letter that is rumoured (!) to be written by Schultz confirms that Starbucks will be focussing on re-introducing that original spirit, as hard as that will prove to be. There's only so much that you can change, after your company has reached a certain size. It would, at this point, be like saying that McDonalds is planning to become your corner-restaurant where everybody knows your name and favourite food.
The innovative angle
A friend of mine made me aware of a new coffee-brewing machine on the market, called Clover, which promises to deliver a higher quality coffee to consumers, though also at a higher price. According to Bruce Milletto, a retail consultant to the coffee industry, "a typical American café spends around $50,000 on equipment, about one-quarter of which goes on an espresso machine. At $11,000, a Clover costs the same again." Thus the investment-proposition is not an attractive one to the average cash-strapped café, who would have to spend that kind of money and charge an expected $6 per cup to recuperate that cost.
Following the rules of mass-production, Starbucks + Clover makes for a match made in heaven, and so it is: Starbucks has in fact acquired Coffee Equipment Company, the four-year-old Seattle-based maker of the Clover coffee brewing machine, for an undisclosed sum.
Considering that Starbucks has long been threatened by the commoditisation of coffee in the US, through the birth of literarily 1000s of new franchisers who, on the surface, provide the same value-proposal, though perhaps at a lower quality and price, it makes sense to acquire one piece of machinery that makes a bit of difference in the eyes of certain consumers. Considering the recent partnership with Apple, I believe that these consumers share a similar taste and price-insensitivity, and since that segment appears to be growing, I believe that Starbucks made the right call. They appeal to the type of customer that will pay $6 for a cup, and with their economies of scale, that price is sure to drop to a slightly more acceptable level of (I guess) ca. $5.
The cultural angle
There is another side to this. The USA is not the world, and while Starbucks has been thriving over there, the Europeans (I can't speak for other continents) have enjoyed a coffee-culture for quite some time. For people like my parents, who are respectively citizens from Southern- and Western-Europe, and avid café-visitors, they would not even consider going to the Starbucks in the centre of their German hometown, because there are plenty of alternatives with more atmosphere, more identity. To them, Starbucks is like a McDonalds, a franchise that in fact shares many cultural values—bringing a good to the masses—and does so by building ecosystems of services—from music-retail to the happy-meal—to deepen the (commercial) relationships with its customers.
Consciously and subconsciously, I'm a sympathiser of "unique" café-outlets. I like spending time in them, sometimes hours at a time, read my newspaper in peace, and enjoy a reasonably good coffee at slightly less than $2 a cup. I don't actually care about spending twice that for a coffee, but all the Starbucks's I've been too (exclusively in Germany and the UK, I must admit), have been so devoid of atmosphere that I don't really spend more than a few minutes there, 30 max. The only thing that does attract me about them and similar stores, is that I can grab a cup-to-go, mostly in the summer, and enjoy it out in the sun.
As a citizen of Europe, I think I am a fan of the heritage of the traditional café and don't really want it to go. If that makes me "backwards" or conservative, I am sorry. I want the chance to enjoy a Turkish coffee in Brussels, an Italian coffee in Cologne, or simply a Dutch one here in Rotterdam. I enjoy knowing the history of a pub that has existed for over a 100 years in Antwerp, and the same in Maastricht, or Amsterdam. I want there to be a diversity, and most important, I want that choice to be mine. I don't want there to be a cloned coffeeshop on every corner.
One of the saddest things I heard, while I was in Belgrade last year, was the exactly such a historical café was replaced by a chain (and the coffee stunk too); and I was equally sad to see that nearly all of the traditional retailers I remember from before the war had been replaced by a cloned shopping-centre that would've made any Western city proud: from H&M to Footlocker.
Opponent: Starbucks?
Globalisation is a situation we must all deal with. Its oldest proponents are the FMCG-companies, who are focussed on producing the same good for millions of people. The question is whether coffeeshops should embrace the FMCG-principles like McDonalds and Starbucks clearly have.
Starbucks is a formidable opponent: it is both a roaster, a retailer, and an FMCG-producer. It is strong in the US, and has a significant presence in the rest of the world. It will not go away, And not all believe that their presence is all that disruptive. I don't either, as long as Starbucks knows its limits. There are parts of the world that do not share the same qualities as US-towns. Some cities have long histories and places of heritage that should perhaps not be housing a McDonalds or Starbucks.
In a way cafés are stuck. They need the kind of innovation that Clover brings, but they are not in a position to buy their way in. If they did, they too would have to become mass-marketeers, in order to recuperate that cost. Instead they need to focus on what they do best, and coffee-machine makers to do the same and just license their technology. And whether the latter is able or willing to do that is the question.
I'm not sure how much Clover was acquired for, no one is. And I'm not sure how far Starbucks is willing to go to ensure their qualitative and quantitative dominance of the market. Will they grab every new piece of technology that promises to introduce a higher quality of coffee to consumers, keep it for themselves, and leave the traditional cafés to differentiate themselves simply by their "culture"? Sheer business-principles dictate that they will.
Howard Schultz made me believe, in his book, that it was Starbucks' mission to bring better coffee to the world. Let's hope that a richer coffee does not come at the price of a blander world.
This piece is in fact incomplete. Optimally I should write up a list of actions for coffeeshops to take. However, I am not yet that familiar with all the business-issues facing these organisations and all of my suggestions would be targeted at growing in size and battling on similar terms as a national or global player. And I'm pretty sure that many would not be willing to do that. So I think I'll wait until I have a more objective grasp—from all angles—on the situation, before giving practical advice. Feel free to provide me with that objectivity through your comments.
 I'm still "on a break," but stumbled across this interesting titbit from a book on warehousing-practices. If you don't like reading lists, too bad because it's interesting, but I've also summarised the key-points in the end.
China
- Low labour and land-cost, but high equipment costs, translate into large (e.g. 250,000 square feet), low warehouses like in the US, but often lacking even a forklift.
- Certain goods like consumer electronics, are of such high value, have a short life-cycle, and thus a lower inventory-cost, that expenditure in state-of-the-art technology is justified.
- Certain cost-saving practices, like removing the pallets from shipments in order to ship more goods, cause some inefficiencies other countries, like, eh, re-adding pallets.
East Asia
- A traditional focus on personal relationships and less on computational models, means there's a lack of data and opportunities for improving performance are not well-developed.
- The most active economic areas are separated by lots of water, which means lots of product conveyed by air (for high-value or time-sensitive products) or ship (for bulky items or commodities). The high costs associated with this, are incentives to consolidate freight.
- Therefore, more strong regional hubs, like in Hong-Kong and Singapore, are expected to emerge.
Europe
- High labour-costs and an inflexibility of the work force have lead European warehouses to be more advanced in terms of automation.
- A growing common market will also lead to more economies of scale in the future, leading to larger, centralised warehouses.
India
- Characterised by cheap labour and land-cost, but relatively expensive capital costs (machinery and the like) and an underdeveloped infrastructure (both physical & administrative).
- The markets being supplied are generally local and not very wealthy, which leads to the SKUs not being high cost and there being little incentive to increase efficiency through capital expenditure (IT).
- Global demand means that larger distribution centres are being built around large ports like Mumbai (Bombay). The lack of land there is leading to high prices, comparable to Singapore/Hong-Kong.
North America
- Characterised by a culture of mass-consumption and a uniformity of the market and distribution infrastructure, which translates into large centralised warehouses and accelerating rates of product flow.
- Warehouses are often situated in the countryside surrounding metropolitan areas, which is cheaper, while being well-connected.
- A good telecommunications-infrastructure enables better supply-chain co-ordination; Warehouse management systems are generally advanced, and the rich data leads to better tracking and performance.
- High labour-cost are off-set by using cheaper migration-workers
Singapore, Hong Kong, Japan
- Due to a lack of land and high labour-cost, warehouses tend to be built high.
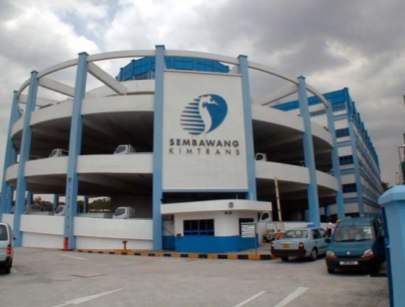
- Elevators are one bottleneck, caused by this style of building, however a Singapore warehouse has found a solution to this: A multi-floor facility with no automation or elevators, but, instead, a spiral truck ramp so that trailers may be docked at any floor (see pic). This does claim more land area, which must be recovered from above, and doesn't work well if trucks have to shuttle between multiple floors.
- While both Singapore and Hong-Kong act as hubs, Singapore is much more international, receiving goods from manufacturers all over Asia and shipping it to other countries; Hong-Kong receives mainly Chinese goods. Also, for the latter, many of the goods come in via trains and trucks, while leaving by ship or flight, while for Singapore it comes and leaves via sea and air.
South and Central America
- Labor costs are low, though not as low as in China, and the nature of its local economy and customers does not justify high equipment expenditure.
- The only exception is Mexico, which can quickly ship products to the US and keep its inventory low, thus justifying state-of-the-art technology.
Final thoughts
Some general conclusions can be drawn.
- Labour costs are a factor when considering automation; automation is a factor when considering optimisation; optimisation is a worthwhile expenditure when dealing with high value goods with a high velocity.
- Cheap land seems a fundamental advantage, looking at the logistical nightmares that Singapore and other high-rise builders must be experiencing.
- Access by land will significantly decrease the cost of transport. Generally, a well-developed infrastructure means more access to wealthy markets and enables warehouses to store high-value/high velocity goods, which is good for them.
The book 'WAREHOUSE & DISTRIBUTION SCIENCE,' which is available as a free download, provides some incredibly detailed info on how to effectively set up warehouses and distribution chains. Well worth a glimpse, if not more.
Cooking is ingredients!… it's timing!… it's cleanliness!… it's… … …restraint!
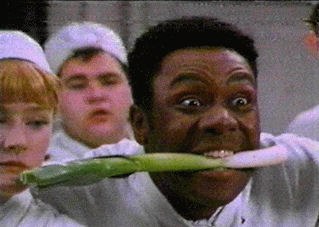 These are just a few of the tips that Gareth Blackstock, chef at Le Chateaux Anglais, and lead character of the British comedy-series "Chef!," delivers to his staff in a kind and gentle manner… not. Even after re-watching this show 10+ years later, I'm still not sure whether Lenny Henry's portrayal of the angry chef is meant to be a realistic, or rather a satiric look at what goes on in these kitchens. The effect it's had on me, in any case, is one of silent terror when I think of kitchens in 2-star restaurants.
There's no denying that, generally, the world of HoReCa consists of flat hierarchies; there's the boss, either the head-manager and/or the head-chef, followed by some type of administrative class of underlings, and finally those that Gareth Blackstock likes to call
"There's the aristocracy, the upper class, the middle class, working class, dumb animals, waiters, creeping things, head lice, people who eat packet soup, then you.."
If you're thinking of high-tech start-ups in the IT-world, multi-star restaurants are their equivalent in the HoReCa-world. Competitive advantage in technology comes from both products that are differentiated enough from the competition and processes that enable a business to produce these products at a sufficiently low cost and high scale to reap a profit.
In restaurants, this is embodied by the chef, whose training, experience, personality, and, I guess, raw talent, inspire fear in all of those around him, especially the ones that feel his wrath. It is an innovation machine difficult to replicate, comes at a high price and is not for the faint of heart.
Everything else: coming up with a business-plan, talking to investors, setting up the site, buying the materials, hiring the people, getting customers to visit, etc.… seems easy, compared to finding, keeping, and managing a good chef. Because as soon as the chef finds out that he is the one that keeps the ball rolling, he is the vital cog in the machine, he will likely fire you as a boss and replace you with one of those people, generally found under head lice and packet soup.
So there you have it; I don't write about cuisine, same as people generally don't think about starting a business in space-flight. They are both sciences reserved for an elite pioneering-class, one that is fearless and willing to risk the laws of nature in order to succeed.
 Let's face it, even with nature knocking on our door, some accountant will still ask what this whole thing is going to cost. Science, facts, morality… it's not enough. I compare it to smoking; even though everyone knows smoking kills, it took pressure—social, governmental, commercial—for people to quit. And the same applies to businesses going green.
Without further ado, here's five pressures that make the business-case for companies to change.
1. Governmental pressure - let's ignore for a fact that government is the one keeping its finger on the pulse of scientific research, social, business, and technological trends. But what is hard to ignore is that the government is actively pushing businesses to change, either by punishing the wrong-doers, by subsidising clean practices and technologies, or by providing new infrastructures around these new rules, allowing for businesses to dispose of their waste in better ways and use alternative, cleaner energy-sources.
2. Consumer pressure - like with smoking, not all consumers have been following the new green "religion" quite as passionately. That said, there are the early adopters, the geeks, the pressure-groups, that are insisting on businesses changing their ways. And those businesses are themselves customers to their suppliers and are doing the same thing to them.
3. Business climate pressure - apart from the above, two things will strongly pressure businesses to change: costs and competition. The rising cost of fuel, electricity, and water, etc., as well as the cost of disposing their waste, is a good incentive to implement technologies that help conserve energy and produce less waste. Similarly, as competition will do the same, businesses are forced to respond.
4. Knowledge-carriers - with the amount of scientific research being produced everyday, it was only a matter of time before methodologies would be developed to help businesses become greener. Since this is still a specialised activity, both commercial parties (consultants) and governmental institutions are there to advise companies on how to change.
5. New technologies - new inventions are constantly being brought to the market, that help businesses conserve energy or get it from alternative sources. Think: technology to monitor and regulate energy-use, water-conserving toilets, more efficient lights, green roofs, etc.
Anything I missed?
In a way, you can't blame businesses for resisting. There have been lot's of change-initiatives these last decades—from ERP to joint ventures—which have produced questionable, if not disastrous results. For change to happen, it must be driven by strategy first, because doing business is like doing war. There is a high price for failure and no one will be congratulating the loser.
But what is certain, is that eventually there will be no more choice. Those that are slow to react will do so at the cost of an unsympathetic government, of the competition racing ahead, and of customers dropping their support.
This article is mirror-posted on tech IT easy, where there's also an interesting discussion going on. Why do people end up going green?
5 links - sense of smell, false green ads, farming boom, Lego, fun e-shopping
0 comments Posted by Unknown at 10:49 AM Time for those Sunday-links again. Today, I'll discuss the cocktail that is smell and how some things just don't mix; how green is not all it's cut out to be; a possible shift of power from retail to farming (or not); how lego came to be and where it is going; and how to sell me online shopping.
Previous link-discussions can be found here and my bookmarks here.
Link 1: Starbucks Admits Sensory Mistake - These are the kinds of stories that make me I like the NeuroscienceMarketing-blog. If you follow the science-section of the Economist, you'll know that neuroscience is a big deal anyway. In any case, this story is about how Starbucks designs atmosphere, largely influenced by smells. Apparently, smell of heating egg and cheese sandwiches doesn't mix well with the coffee aroma.
Link 2: False 'Green' Ads Draw Global Scrutiny - Two problems linked to green adverts these days, I think. One is that consumers are growing tired of it. And two is that, as this story shows, just because companies say they are, doesn't mean they are. I like the Norwegian approach to this. They ban green adverts by products that cause more problems, no matter how innovative they are (about hiding it).
Link 3: Farmers Wonder if Boom In Grain Prices Is a Bubble That food-prices are rising is an inescapable fact. But it also presents an interesting shift in the status quo. In the food-chain of the grocery-business, farmers are pretty much at the bottom. Now, even though their own costs are increasing also, they can charge more on top of it and decrease retailers' margins. Time will tell if this is something that will be acceptable for a long time. Certain signals very much suggest to me that farmers may be in the right position to cut out the middle-man and become retailers themselves.
Link 4: The Making of…a LEGO - I'm still a kid at heart, so I love anything to do with games and toys. My parents never bought me much lego as a child, which I regret as I hear it breeds geniuses. In essentially two pages, the article describes how lego came to be, what makes it so perfect, and what the company's strategy is. I was always impressed with the brand-extensions they did with the games, the robots, and the theme-park. A company to follow.
Link 5: Online shopping at Hema.nl - I've linked to this on twitter before, but it brought another smile to my face watching it again. Just when I think that online-shopping has no future, innovative uses of technology surprise me again.
The role of the internet for the retail of *physical* goods.
0 comments Posted by Unknown at 9:01 PMOne of the stories, I covered last week in my links, uncovered an interesting statistic. Only about 3% of retail sales in the US happens online. I don't think these stats are at all coincidental. While I see a bright future ahead for the online retail of media-products, I find that what the internet cannot provide, is the "closeness," that is sometimes needed for evaluating certain types of goods, like food and clothing. I have commented on this before, implicitly, with a post on the web as a third place, and about the lack of cohesion that Facebook provides.
At the same time, as The New Yorker story reports, what the internet has changed is how we shop; it is much easier to research and comparison-shop than it was before the internet-days. A survey by Accenture found that ca. 66% of those surveyed compared products online, and another study showed that the internet played a significant role with ca. 75% of electronics purchases.
IInnovate has an interesting podcast interview with Scott Dunlap, CEO of NearbyNow, which has come up with an interesting way to exploit the informational advantages of the internet and mash that with the qualities of physical shopping. Following short video shows how their service works:
Clearly technology has evolved a lot in the last few years, making this possible. NearbyNow works via the web and via mobile. I'm not sure if they are using any location-tracking & matching services, but certainly they are heading in that direction. On the retailers' side, there is plenty of technology that makes this possible also. Electronic inventory and point of sale systems allow both for the checking of stock-levels and for consumers to reserve items to be picked up and tried on at a later date.
One issue that entered my mind, is that of efficiency. The way NearbyNow operates is through malls in the US, most of which are, as I found out, owned by 6 major companies across the nation. US's scale-economies win again! In Europe, the situation appears a little different. Culturally, linguistically, technologically, and legally, it is a much more fragmented market, with far fewer malls also, and that may make it difficult for a unified service like this to operate as efficiently as it would in the US.
There is also the issue of too much transparency, which is worrying to some retailers, and addressed in the podcast-interview. But what does seem certain is that this is exactly the type of service that consumers value, and as such one that any consumer-centric business should encourage.
Will a service like this ever replace shopping in its entirety? No, I'm essentially betting my future that there are plenty of qualities *real* environments will continue to offer over virtual ones. But there is no reason, none at all, to try to integrate the good qualities that the web does possess—information at your fingertips—as elegantly and effectively as possible into those experiences.
 One of the things I do on this blog is deciding on the potential of industry-segments, ranging from farming to coffee-shops, and from grocery to other types of retail. On Tech IT Easy I've previously expressed my scepticism at media (in which I include text, art, audio, video, and gaming), especially in terms of business-models, which I think that segment lacks.
Equally so, I see fairly little space for it in the physical retail segment, simply because it is so much more convenient to purchase and consume it via digital means. The PC (and other tech-gadgets) have essentially become the hub for all things media, and creating barriers to that experience just leads consumers to pursue more convenient ways of experiencing that media. That search for convenience is something that I've also approached in a previous post on this blog.
Let's look at some media-types and how they are being sold online.
For Video - there's iTunes, consoles, and set-top boxes that are controlled by media-producers. In any case, the power-differentials between producers and intermediaries is very unbalanced and it isn't a nice segment to enter as a retailer. Also, let's not forget the free alternatives: YouTube et. al and piracy.
For Audio - again iTunes, Rhapsody, and Amazon MP3 Store, but also smaller digital store for independent artists, like CD-Baby (which operates through iTunes also). Let us again not forget piracy and the fact that much of music is being produced through digital means and it makes sense to organise distribution that way also.
For text - there's again online outlets like Amazon for eBooks (Kindle) and Zinio for magazines. And let's not forget that 99% of text-based media is viewable for free online. Still, admittedly, electronic devices for consumption are not yet able to compete with paper-based methods, at least where price is concerned. Also Audible should not be forgotten as a source for audio-books, recently bought up by Amazon and partially distributed through iTunes again.
For Gaming - I'm not too familiar with the online market for this one. Even so, there's Steam, a digital distribution system by Valve, a platform which they recently opened up for use by other game-publishers. There's also plenty of smaller games being distributed through Xbox-live, the future Playstation Home, and of course the internet.
Finally, Art - here the situation is more complex, while on the other hand being relatively simple. It is complex for artists like my mother, who paints, and conducts business on a personal level by interacting with her customers. On the other hand, there's photography and digital art, arguably the evolution of traditional art, which is easy (for some) to produce digitally and distribute online. I suppose every industry has that friction between the traditional way of doing things and "the new way."
All in all, I don't see media as a big cash-cow for physical retail. I like to think that, because production and distribution becomes cheaper, that its cost will eventually fall to a very low price, allowing for it to be included as an added-value component in the service-proposition of physical retail-outlets (to which I also include restaurants, etc.). I also like to think that creating environments that make the consumption of media a comfortable process (e.g. cinemas) also has some potential.
But my outlook for selling media as a product, something that could easily be sold digitally, remains bleak. Please let me know if there are arguments against my point of view, as I'm here to learn.
5 links—retail-saturation, RFID's costs, elements of fun, tricking shoppers, & home-cinemas
0 comments Posted by Unknown at 10:41 AMIt is time for those links again! This time, we'll be discussing the economics of Apple's physical stores, how Walmart is enforcing RFID, how retailers are trying to trick people to buy more expensive things, how people perceive fun in games, and 10 ultra-geeky home-cinemas.
As usual, my bookmarks can be found here, and the previously covered links, here. Enjoy!
Link 1: Why is Apple saturating (US) cities with retail stores? is a question that Choire Sicha asks on Kottke.org, and lead me to this profit & cost breakdown of Apple's retail stores at Seeking Alpha (see pic below). It does appear it's all about the money, though hard it remains to read Apple's mind 100%. In related news, OObject lists all the items needed to build an Apple store.
Link 2: Is RFID economically feasible? I'm planning to dedicate at least 1-2 posts on RFID on this blog in the future, as I've essentially been following its development since the early coverage on Slashdot. This story on InformationWeek discusses the pressure that Walmart, certainly the biggest champion for RFID in the retail-arena, is putting on its suppliers to finally add RFID into their logistics-chain. As far as I remember, the latter have been complaining about the unfair balance of cost that RFID causes, shifting most of them onto suppliers. I assume, however, that these chips and pallets are reusable.
Link 3: What makes games fun? Lightspeed Venture Partners has an interesting blog, which mostly discusses the business and principles behind digital games. I follow it because games are fun, and if you can understand the source-code of fun, you can replicate it elsewhere. In that spirit, then, it links to an interesting white paper trying to map out what exactly goes on in gamers' heads while playing games. Part 1 is also very much worth a read.
Link 4: A buyer's christmas? The New Yorker digs into consumers' buying behaviour. Interesting is, that people use the net most often to find info, not to buy, but can use that info inside stores (we'll still need ubiquitous internet for it to be shoppers' utopia, however). Equally interesting is, that if a store has two microwaves, consumers will usually buy the cheaper one. With three products, however, they will usually by the mid-priced one. There's still room for trickery, I guess…
Link 5: 10 stunning ultra-geeky home cinemas. In the spirit of my previous post on cinemas & luxury, I thought that this link would be fitting. The Star Trek-themed one is a little too geeky for me, but the Titanic one (no. 6) looks awesome. I'm still doubtful about whether it's about the design or about the movie, but I can't deny that people put a lot of work into designing these.
I'm writing today's post mostly as a way to relax me. I've been in a bit of a panic these last few days because my main machine, my trustworthy mac, is giving me kernel panics and I'm in the middle of a project. It's not a nice feeling, and any repairs, I've been informed, are bound to take 10 days. So, blogging to relax, yes, but don't expect regular ones, especially considering this machine can "explode" at any time. NYTimes recently wrote about a strategy employed by US cinemas to draw in more people. I quote:
"Reserved seating, plush rocking chairs and made-to-order food make Mr. Redford’s Sundance Kabuki theater feel more like a restaurant than a traditional cinema. It also has a 50-foot-high lobby with live bamboo, a glass atrium and reclaimed wood walls. Here, a night at the movies is less about enduring the hordes at the mall and more about feeling pampered."According to the article, big US-chains are building such upscale cinemas to draw people back into the experience.
While I am a big fan of the cinema-experience and actually worked at exactly such a venue, years ago, as a cocktail-mixing barkeeper, I think there are several reasons why such a strategy won't work.
The nature of movie-viewing (1): regardless of how luxurious a place like that is, you'll still have to sit in a dark room and won't actively notice the luxury or people around you, except for before and after the movie. The reason why people like dining in luxury-restaurants is because of the luxury, yes, but also because you share it with a group of people. In cinemas, luxury is not an emotional draw.
The nature of cinemas: cinemas are still very much in a mind-frame of providing experience of the masses. That manifests itself in a McDonalds' mentality of serving guests standardised services, having a lot of seat-rotation, cleaning big rooms (badly) in less than 10 mins, etc. It's a lot of little things, but they add up to a reputation for mediocrity, and people really just come to view the movie and be with their friends.
The nature of movie-viewing (2): YouTube, the internet, modern lifestyles, etc. have created different viewing-patterns, and there is a much greater focus towards viewing media in bursts. I think that the cinema-industry thinks that it is competing with some kind of emulated experience at home, but I don't think that's generally the case. So what are cinemas competing with and should they compete with it?
Luxury is not mass: Cinemas need masses of people coming in, and luxury cinemas actually only aim to address the (imagined!) needs of a few. In my opinion, it is not a customer-focussed strategy, and is for that reason alone bound to fail.
What should cinemas do?
Now, I'm not all against a certain level of luxury. I like comfortable seats as much as the next guy and I'd love a good cocktail every once in a while. But I think standards should be upgraded throughout the cinema, all the way down to the lowest seats, and that everyone should have the option to get a cocktail (if they have the budget).
There's two main selling-points for cinemas, I think, and those are timing and technology. They are still the first to air a film (ignoring piracy), which will hopefully not change. So, for blockbusters, cinemas reign is pretty much guaranteed.
Apart from blockbusters, there's something special about seeing indie movies in cinemas, which I include into timing. I'll never forget watching "Howl's moving castle" in the cinema, it was a magical experience, one that I could never have at home.
As far as technology is concerned, admittedly we are in an age where big screens and high-def visuals and sounds are becoming commoditised, though no one is as yet planning to install a 50 ft. screen in their house, afaik. I do think that cinema-technolgy should be upgraded, all the way to the point of the IMAX-experience.
Admittedly, there are some problems with 3D-tech. It increases the cost of producing a film and won't translate well to home-viewing (I think). But my point is that cinemas should keep differentiating themselves technologically.
People is a third selling-point, though I think that unless you like going with 8+ people to the cinema, you will be able to emulate that at home.
As far as luxury is concerned, again the basics should be present, and cinemas have to make money, but cinemas would become a lot more popular if they kept the price of seats down, increased the quality of service, and charged what they charged for luxuries. The one thing that I can't stress enough is staying a leader in technology (video & audio) as that is truly where the emotional draw for cinemas comes from.
But maybe I'm wrong!? Feel free to let me know in the comments.
5 links - cool vs. tech, touch-screens, women, pizza, & bookstores
0 comments Posted by Unknown at 12:09 PMMan, I collected so many links, that I'll probably have to write three updates to cover the most important ones. We've got a lot of ground to cover, so let's get started. You can find my previous coverage on interesting links from the web, here, and my continuous stream of bookmarks, here.
Link 1: On Magnetbox - Correlating cool with tech - With pictures like the one below, my work on this blog is really done. Interesting is the rise of computers vs. dance & hip-hop music (both of which are hugely benefiting from the cost-savings made possible by PC-based studios. (A note: low industry-barriers = high chance of suckage!). Also note the fall of art, after the colour TV was introduced. Kottke also made some comments about it.
Link 2: On BuzzFeed - Touch-Screen Ordering - BuzzFeed presents us with some stories about automatised ordering. There are both advantages and disadvantages, I think. Good is that it minimises errors in ordering and can interface well with back-office operations, such as ordering new supplies. It might also fit with the individualistic preference for self-service, I wrote about before. The disadvantage is the cost and the margins of error that information systems bring (I still shudder at the thought of the LAS disaster (pdf)) + the lack of the human factor. Martin Kunzelnick (German) links to some videos of Microsoft's Surface in a restaurant-environment.
Link 3: On Lightspeed Venture Partners - It is no accident that Typhoid Mary was a woman - Although it's a horrible-horrible title, and perhaps an obvious point, I've been coming across many stories about the social qualities that women possess, making them better at PR, marketing, sales, relationship-building. Something to keep in mind for any people-based business.
Link 4: On Reuters - Pizza Hut rolls out nationwide mobile ordering - A news-item (finally), and I'll probably delve into this topic sometime in the future. Arguably, Pizza Hut has been pursuing a different strategy from pretty much 98% of the pizza-restaurants out there. I'm sure that there is considerably brand-loyalty towards Pizza Hut, which will give it an advantage over delivering pizza-franchises, HOWEVER, it will probably be competing on price, which the franchise has not done so far. I'm not sure how that will affect their brand at all, but it's something to keep an eye on.
Link 5: On WSJ - Who's Buying the Bookstore? - arguably, there are few retail-outlets that evoke such an emotional response as bookstores. I find them comforting, and very similar to churches, in the way that it really is expected of you to be silent while browsing (on a side-note, I discussed a link of Dutch bookstore being opened in a church before). It's also a symbol of a community, as WSJ points out. Well, with competitive pressures from Amazon et al., these types of stores are clearly disappearing, or changing into hybrid monsters, which smaller stores can no longer compete with. WSJ points out a phenomenon related to that community-spirit, which is very touching. Capitalism isn't everything, particularly in places that target the softer pleasures in life. I'll have to reflect more on this, as I'm very attracted to these types of stores, and would love to set one up myself.
That's it, for this week. I'll see how I'll catch up on the rest of my links, but this went great (took 20 mins), and I always enjoy re-reading my bookmarks. I hope you do too.

 The


