 I'm still following my tradition of looking back at what I covered and processing it into a blogpost. The general aim is for me to process the stuff I wrote about before, and give a reader some compressed value of an otherwise unforgiving linear medium. Time waits for no-one.
Why did it take so friggin' long?
For Months 1 & 2, I did so on a monthly basis. Later on, I was interrupted for study-related reasons, so hereby a 3 month summary (though only about 6 weeks of real activity).
Now, if month 1 can be categorised as a focus on market research, design, core-values, the value chain, and trends in FnR, and month 2 on human resources, business strategy, branding & marketing, innovation, and finance, months 3-6 aimed at news & trends, operational issues, marketing & branding, entrepreneurship, and strategy. Phew, what a mouthful… this is going to be a long post, so let's get started.
Micro-topics
Following three headings cover, what I call, micro-topics. They delve into specific situations (news & trends) or issues in running a business (operational, branding & marketing).
News & Trends
I noticed a decreased focus on news these months, simply because I didn't want to re-blog other people's stuff, and found conceptual lenses, and micro-topics more interesting. Also, my links often covered some news, as do my continuously updated bookmarks.
Nevertheless, I tried to identified some trends, namely private labels, organics, and SEPA, which I discussed at some greater depth. For Private labels, I looked at what regions and product lines were doing best, and came to the conclusion that there's huge potential in terms of lifestyle-products and offering higher quality goods than manufacturers can, simply because of the savings in marketing. I discussed lifestyle in a number of other posts, but I will go into those later on.
For organics, which has seen a huge upsurge in the last 5 years, I remain bearish, simply because I see it as a very inefficient, resource, and human-intensive process, that, in combination with the high energy-costs and rising food-prices, may not appeal to consumers increasingly shrinking wallets. That said, innovations are usually inefficient at the start, organics fill a certain need, and more automisation in such production-methods may dissolve many of my arguments.
I also looked at SEPA—the single European payment area—which was just launched (and you should be seeing an option to pay via SEPA in your internet-banking site now). Arguably the most boring post, I've ever, ever written (well, there are some contenders), but since I want Europe to be a single market so that businesses can finally benefit from the same economies of scale as the US, China, India, and Brazil, I thought it be important to discuss it.
Microscopically, and just for fun, I also identified some trends in terms of cinematics, beers, and pie, as well as a changing perception of expertise (more on this when I discuss entrepreneurship later on).
Operational
A second focal point was on operations of food & retail-outlets. I'm fascinated by optimising internal processes of businesses, so one of the topics I focussed on was whether it would be possible to use lean Toyota principles in a Food / Retail environment. I think it is, but at the same time, should not act as a replacement for customer-service. Granted, competition is fierce and any cost-savings should be welcomed, but the differentiating factor should be the amount of cherries on top: service-quality, product-quality, etc. I still need to read the book, though, and I definitely have more to learn/write about this subject.
I also looked at real-estate, fairly extensively, though some topics for future exploration remain. Clearly one of the biggest pains for FnR-venues is location, location, location… (it is also an inherent strategic component to large franchises like McDonalds) and I started with looking at structuring search and using checklists. In a second post I looked at the competitive/cooperative context of choosing a location, and in the third post, I looked at a number of costs that are part of the location choice.
Marketing & Branding
M & B is a continuous micro-topic of mine, even though I don't consider myself a marketeer. Two of my favourite topics include "the service paradox - on self-service and customer-rentention," which discusses the strangely liberating effect that no service has on today's individualised customers and positively affects their loyalty in return… talk about an eye-opener, for me at least… and "Lifestyle products - the costs of educating a market," which looks at the significant marketing-costs associated with starting a company in an unmapped market. As for the latter, I'll definitely be writing more about the particularities of lifestyle-products pretty soon.
The other three topics were interludes—hence the reason why I don't consider myself an expert. I wrote about how much of marketing is based on arguments, how arguments are often designed to distract or confuse an audience, how the consumer is overwhelmed with them, and how their value is ultimately decreased drastically. Very abstract… I also proposed that this is exactly why simple products work exactly so well: kill the argument.
Two more interludes include a review of Malcolm Gladwell's books, which both offer great insight into how people think (and how to market products), and I re-blogged "a marketing plan in a nutshell," kindly provided by an MBA-student at MeFi, which should be useful as a general reference.
Macro-topics
Following are topics that are core to what I write about: entrepreneurship and strategy. The first aiming at starting, running, and growing FnR-related companies, and the second at the bigger picture: taking an industry-perspective, how to interact within the context of a value-chain, core-pains, etc. There is also considerable overlap between the links I discuss now and those that came before.
Entrepreneurship
Looking at my eship-posts, I found that I often take a more personal stance at issues, compared to other disciplines. I think that's related to that the human element is stronger in these businesses, something I found out from speaking to many start-ups, incl. ca. 300 start-ups for my thesis.
In "The business of HoReCa - Hotels, Restaurants, Cafes," I discuss the issue of semantics in regards to choosing a vocation, and the perspective of my father, who helps me think about this area a lot. This is somewhat contrasted by my post on my own generalised (vs. specialised) look at the food & retail-industry, in the sense that I care more about the big picture (for now at least). I'll come back to this in the future, I'm sure.
In my post on "lifestyle-products," which I mentioned before, I also try to approach the topic of starting such a business in a second-world country, through a friend's eyes. Similarly, my post on "How being in the right place at the right time translates to starting a business," takes a very personal, and perhaps subjective approach to the issue.
Some micro- and just-for-fun topics include the "10,000-hours-to-be-an-expert rule," in which I identify a trend that's pretty similar to crowdsourcing expertise. On Tech IT Easy, Georgia Psyllidou discusses a similar phenomenon about how people can find work nowadays, and I think I will approach this topic again in the future. Call it semantic, crowdsourcing, open innovation, etc., but the world is changing, it is getting flatter, which has both implications to finding human resources, as well as distributing knowledge. For instance, in a recent article on HBR, the topic of authentic leadership is discussed entirely from the perspective of 1000s of examples. Worth a read and thought-inspiring!
Another fun topic was the Lowest Common Denominator (LCD). I first approached this abstractly, while under thesis-stress, but I find it a useful way of thinking about simplicity of action. What is the simplest, most basic feature that your product needs, that your strategy needs, that your company needs to work? Later on, I explored this again concerning my friend's lifestyle-business.
The strategic lense
Strategy has always been difficult to conceptualise, I felt, because there's strategy to everything—war, running a business, running your life, getting the girl, etc. That's perhaps the reason why I never got around to writing a thesis for it, and chose entrepreneurship instead.
I discussed IKEA a number of times in my blog, and one strategic issue I approached, were the early years of growth for the company. My philosophy concerning business is that, generally, "where you are from and when you are from matters a great deal to where you are going," and the same applies to IKEA. Of course, IKEA went far beyond Scandinavia, and I hope to get around to discussing the later expansions the company went through.
Amazon & Jeff Bezos was another topic, in which I wrote about Amazon's approach to innovation (very customer-focussed) and Bezos' transformation from entrepreneur to CEO (from micro to macro, challenging for many).
Another topic was the growth strategy of Starbucks (wholly-owned), vs. that of Subway's (franchise), which is clearly receiving a lot of flack these last months. In the article, I commented on some of the reasons given by other smart people, about why these strategies differ. Some good economical reasons were given, however, none, I felt, went into the roots of the issue. Two factors affected Starbucks' strategy: the roots of the business and the roots of the founders.
Somewhat related, a few weeks ago, i discussed the intriguing strategy of Metro-Group, which has placed two electronics-chains into the European market, Media Markt vs. Saturn, seeming to everyone as competitors. Turns out they are the equivalent to a franchise-system (though certainly a more complex one than Subway), which I think are meant to saturate the market.
Some just-for-fun topics included another post on the lowest common denominator, which I felt was a good lens through which simple strategies can be designed; two posts (1 & 2) about big pains the food-industry is feeling (and which ties into my post from yesterday; and why fitness studios are employing such restrictive contracts, which I felt was caused by either an inelasticity of demand or because they were in trouble.
Clearly a number of other topics fit within the strategic paradigm, but I'm not going to discuss them here.
Wrapping up
What about those Sounds?
I'm considering dropping the "Sounds" from S+FnR, however, it is still a very strong topic in the back of my mind as I'd like to work in venues where people dance… No, seriously. The way I'm looking at it is that I have to focus on certain basics first, and music & media will eventually pop up. So the title stays as it is.
Final thoughts
The nice thing about blogging is that you can measure your progress. I measure them both by readers, by feedback, and by my own perception. During the first months, I was very much in the dark about this industry, and to a degree, I still am. But I notice that things start making more sense, there is a certain logic to how processes work, why certain business models are chosen, etc. So, mentally, for me, there is a certain growth and I hope I can continue at that rate in the future.
I'm still on a certain trajectory in my mind, regarding the amount of secondary and primary activities I have to do to reach new levels. On the latter front, I definitely have a much better idea of where I want to go, after having blogged/thought/discussed about these topics for so many months.
That is all! I can enjoy my weekend, enjoy yours, and until next week.
If you read further into the ACNielsen-report (pdf), I wrote about two days ago, you'll have seen that retailers' private label-strategy seems to be focussed on certain key-areas, namely:
- General health
- Weight-loss
- Organics / Fair Trade
- and Food for kids
At the same time, there are lot of savings on the marketing side for private labels. Retailers are in fact huge market research factories—every move that a customer makes in their store, with their products, can be entered into a database and used for future marketing strategies.
And having full control over shelf-space, shelf-placement, and in-store marketing means that the budget for these can be minimised.
All of which has three implications:
- That more of the budget can be allocated to the quality of private label products.
- That it pays off to have an elaborate in-store-system to collect consumer-data.
- And that independent product-manufacturers are perhaps screwed.
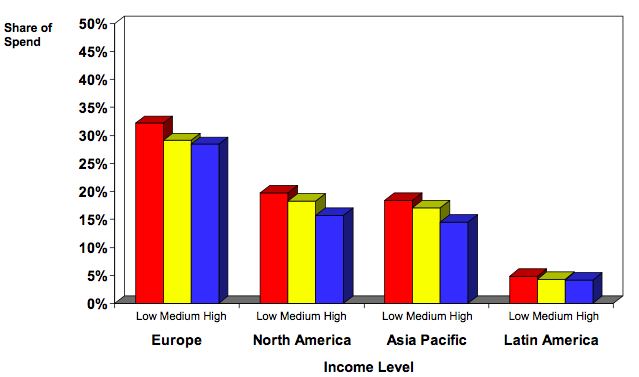
Figure 1: Private label share of spend segmented by income level (source: ACNielsen, 2005)
Of course, this doesn't mean that independent product-manufacturers are completely screwed. It puts pressure on them to become more innovative with their products and marketing than they ever were before. Which is the right kind of pressure.
Final thoughts
There's not much not to like about private labels. In many ways it's a more efficient system. Less time and money needs to be spent on the marketing-side, and more can spent on the back-end—the production. At the same time, independent manufacturers will have the advantage of flexibility. They can (perhaps) adapt quicker to market-trends, or perhaps even lead them.
Not all market-research needs to happen in the store either, some also needs to happen where the consumption happens—at home or elsewhere. And large independent manufacturers perhaps have a better foothold on general trends in society, than retailers, who are mostly restricted to what happens in their store.
(On a related note, one of my early posts on this blog discussed P&G's strategy towards shopper-marketing, worth checking out!)
So it's perhaps not a black-and-white situation. But I think that, looking at Starbucks, which is essentially a private label, that this strategy has considerable merit, because it gives retailers a lot of power over the quality of these products and how these are sold. It essentially shifts the brand up towards the retailer, instead of it remaining on the product-level.
More on this as I come across it.
Essentially private labels, also sometimes called house brands, are products branded either with the name of the retailer, or, at times, sharing some kind of umbrella-name, decided by the distributor or otherwise. But what private labels really represent, to me, is the ultimate example of a power-struggle between a retailer and suppliers. Sometimes, but not always, it also means that some kind of vertical integration has been taking place between retailers and manufacturers, or, at the very least, packaging plants.
For now, I'll just be looking at some stats on private labels. At a later date, I'll take a look at more supplier-retailers dynamics, branding strategies, etc.
Geographic share
According to an ACNielsen report (pdf), the global* market-share for private brands was 17% in 2005 (* global meaning 38 countries and 80 categories), and had grown 6% that year.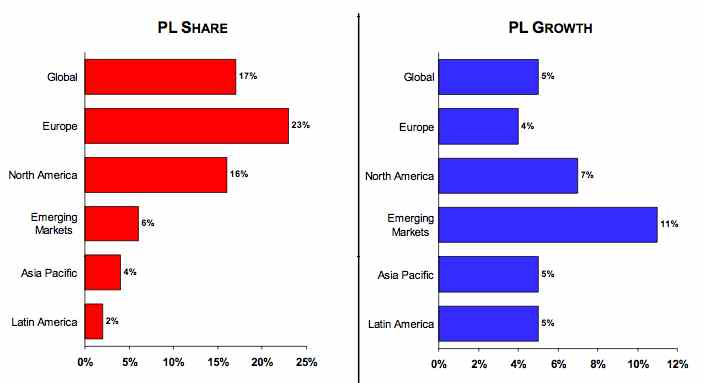
Figure 1: Share & growth rates of private label by region (based on value sales) (source: ACNielsen, 2005)
Europe has the largest market-share with 23%, and Latin America the smallest, with 2%. Top countries included Switzerland, with 45%, Germany, with 30%, and the UK, with 28%. The largest Private Label growth happened, unsurprisingly, in emerging markets (11%) like Croatia (77%), Greece (24%), and Thailand (18%).
One big growth-contributor in Europe is the strong growth of hard discounters, such as Aldi or Lidl (both German chains), who are present in every European country and expanding rapidly. With Aldi, for instance, private labels make up 95% of sales.
Private label foods
Category-wise, refrigerated foods have the largest overall share of private labels, namely 32%. Complete ready meals take the lead here, with an average of 47% private label-share. In the UK, 97% of ready-meal sales are in fact private label.
Another significant private label food, or rather drink, was milk, of which private labels make up 43% of sales.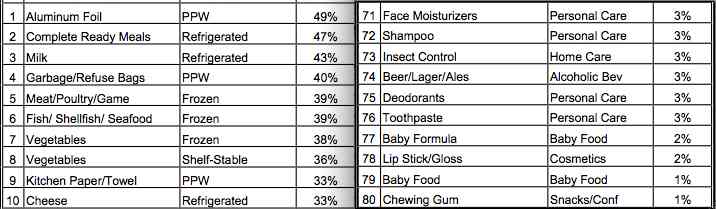
Figure 2: Value shares of private label by category (source: ACNielsen, 2005)
Other high private label food-products include frozen meat (39%), fish (39%), and vegetables (38%), and 37% for shelved vegetables. Frozen pizza is at number 27, with 17%, tea and coffee at numbers 37 and 38, with 14% and 13% respectively. Wine is at number 44, with 12%. And Beer is all the way at the bottom, at number 74 with 3% !
Among the fastest growing foods are drinking yoghurt (28% growth), baby food (20%), chocolate (13%), and water (13%).
Pricing trends
One of the strengths of private labels is of course that they are cheaper, on average 31% less than manufacturer brands. Emerging markets showed the biggest discount, with PL-goods costing 41% less on average. Europe wasn't lagging in this respect either, with an average price difference of -37%. On a country level, Greece, Australia, and Germany were taking the lead with, respectively, -48%, -47%, and -46% discounts (compared to manufacturer brands).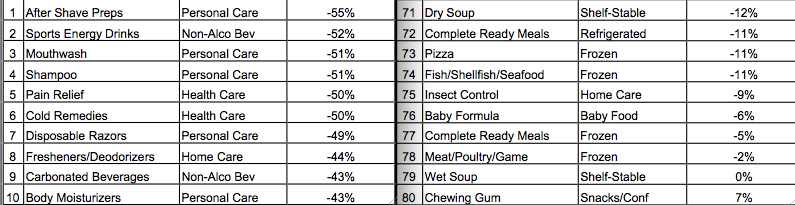
Figure 3: Price differential of private label by category (source: ACNielsen, 2005)
Again, concentrating on food-categories, the products that received the biggest discounts were Sports Energy Drinks (-55%), carbonated beverages (-43%), cereals (-40%), wine (-38%), and tea (-37%). Food-categories taking the least in discounts, included chewing gum (+7%), wet soup (no difference), meat (-2%), and ready meals (-5% <- I guess that explains their high market-share).
Final thoughts
That market share is increasing more quickly in emerging countries is not surprising. Retailers there will likely not be mature and/or consolidated enough to focus on such a strategy, but this is clearly changing.
Germany's dominance is also interesting, as both Aldi and Lidl originate from there. One of my next posts will be on Ikea's European growth and Germany's also very strong there, which suggests a certain preference for low prices with German customers.
Switzerland is still somewhat of an enigma, but I'll try to find out more about it.
In terms of products, both the dominance of private labels amongst ready-made meals, and that their prices are quite similar to regular brands, is very interesting. It could suggest that customers either don't care much for quality and brand-differentiation in that sector, or that private label brands are actually quite good. The price-level would suggest the latter conclusion.
Generally speaking, refrigerated goods are different in the eyes of consumers, I think, less scrutinised perhaps, and worthy of more investigation. Milk is of course similar to water, and hence not really a product where brand makes a huge difference.
What else? Certain beverages, like coffee, wine, and beer are quite interesting, as their private label share is quite low. This would suggest a high brand-sensitivity in these sectors. The low percentage for beer (3%) is certainly striking.
More on private labels as I come to it.

 The


